Categories
Leaders

Tata Sons defends N Chandrasekaran’s third term

Tata Sons has rejected Tata Trusts chairman Noel Tata’s objections to N Chandrasekaran’s reappointment, saying the decision to give the chairman a third five-year term was legally valid and followed the company’s Articles of Association. The company has backed its position with legal opinions from former Supreme Court judges and senior counsel, deepening an ongoing corporate governance dispute within the Tata Group.

The latest development follows the September 17 meeting of the Tata Sons board, where Chandrasekaran’s reappointment was approved. Four directors voted in favour, while Noel Tata, one of the Tata Trusts’ nominee directors, voted against it. The other Trusts nominee, Venu Srinivasan, supported the proposal. With the two Trust nominees split, Harish Manwani, who was chairing the meeting after Chandrasekaran recused himself from the discussion, used his casting vote in favour of the reappointment.

Noel Tata subsequently questioned both the voting process and the legal basis for the decision. Tata Trusts has argued that the support of a majority of its nominee directors was separately required under Tata Sons’ Articles of Association. Since the two nominees voted differently, the Trusts said that condition was not met and could not be overcome by a chairman’s casting vote. Tata Trusts collectively owns about 66% of Tata Sons.

Tata Sons has now taken a different legal view. In a letter to Noel Tata, the company cited opinions from former Chief Justice of India Uday U Lalit and former Supreme Court judge B N Srikrishna. It also relied on an opinion from senior advocate Sudipto Sarkar, which had been obtained before the board meeting. The opinions support the validity of the board resolution and the use of the casting vote.

Justice Lalit’s opinion said that because there was an equality of votes among the directors appointed under Article 104B, the presiding chairman could exercise a casting vote under Article 121. Justice Srikrishna similarly concluded that the proceedings were consistent with the wording and intent of Article 121. His opinion also said a director’s statutory fiduciary duty to the company would take precedence over a contractual duty to the entity that nominated the director if the two came into conflict.

That interpretation also addresses why Venu Srinivasan voted in favour of Chandrasekaran despite Noel Tata opposing the move. Srikrishna’s opinion said Srinivasan had acted in accordance with his fiduciary responsibility to Tata Sons. Tata Trusts, however, has maintained that Srinivasan’s vote could not remove the requirement for affirmative support from the Trusts’ nominee directors.

The dispute also centres on Article 118 of Tata Sons’ Articles of Association, which deals with the selection of a chairman. Noel Tata’s position is that this provision should have governed Chandrasekaran’s reappointment and that a five-member selection committee, including three Trust nominees, should have been involved.

Tata Sons has rejected that interpretation. Sarkar’s legal opinion said Article 118 refers specifically to the selection of a “new chairman” and does not apply to the reappointment of an incumbent chairman. Chandrasekaran remains chairman until the end of his current term in February 2027, according to the legal reasoning cited by Tata Sons.

The disagreement has also brought two different legal opinions into focus. Noel Tata had presented an opinion from former Chief Justice of India D Y Chandrachud, which supported the Tata Trusts’ interpretation that the affirmative support of the Trust nominees was necessary and that a casting vote could not substitute for that requirement. Tata Sons has relied instead on the opinions of Lalit, Srikrishna and Sarkar.

The issue is now expected to move beyond the boardroom. Chandrasekaran’s reappointment as a director will require shareholder approval at Tata Sons’ annual general meeting, which is expected in the coming weeks. The outcome of that process could become an important next step in determining how the dispute develops.

Chandrasekaran, who became Tata Sons chairman in 2017, began his second five-year term in 2022. His third-term reappointment comes at a time when the relationship between Tata Sons and Tata Trusts is facing closer scrutiny over governance, shareholder rights and the balance of authority within the group.

The immediate disagreement is centred on a narrow question of corporate law — how Tata Sons’ Articles of Association should be interpreted when Trust nominees disagree and whether a casting vote can resolve that difference. But the dispute has wider implications for the governance structure of one of India’s largest business groups.

Tata Sons has maintained that its directors acted in accordance with their fiduciary duties and that the September 17 resolution was valid. Tata Trusts, meanwhile, continues to challenge that interpretation and the validity of the reappointment process. With competing legal opinions now on record, the next stage of the Chandrasekaran reappointment row is likely to play out through the shareholder process and potentially further legal scrutiny.
 

Categories
Leaders

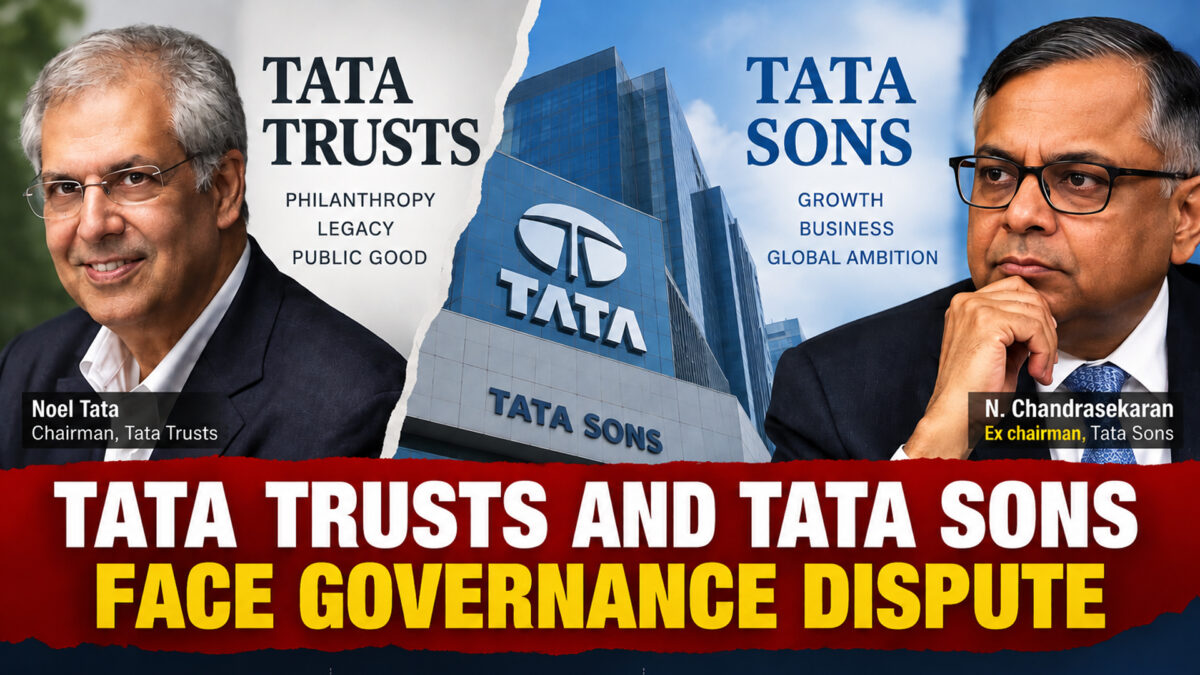
Tata Sons listing faces Trusts’ opposition

Tata Group is facing a major governance debate over the future of Tata Sons, its principal holding company. At the centre of the dispute is whether Tata Sons should become a publicly listed company and how the group should manage its relationship with Tata Trusts.

Senior advocate Harish Salve, who is advising Tata Sons chairman N Chandrasekaran, has backed the case for a public company structure. He has argued that Tata Sons needs to comply with regulatory requirements and that a listed structure could provide greater transparency.

The disagreement comes after the Reserve Bank of India rejected Tata Sons’ request to give up its registration as an Upper Layer Core Investment Company (CIC). The decision has increased pressure on Tata Sons to consider a stock market listing.

Tata Sons had sought to surrender its registration after arguing that it no longer met the conditions requiring it to remain registered as a CIC. The company had repaid its borrowings in 2019. However, the RBI’s position is that Tata Sons continues to meet the regulatory criteria because several companies in which it holds significant stakes have borrowings.

The regulatory status is important because companies classified as upper-layer CICs are subject to additional oversight. The framework also includes requirements relating to governance, capital and risk management.

A public listing could therefore become one route for Tata Sons to address the regulatory requirement. The issue, however, is complicated by the company’s unusual ownership structure.

Tata Trusts collectively hold about 66% of Tata Sons. The trusts have historically played a central role in the Tata Group and have special rights under the company’s Articles of Association.

The trusts have opposed a Tata Sons listing and have argued that alternatives should be examined. Their position is linked to concerns about preserving the long-standing structure and purpose of the Tata Group.

Tata Sons, meanwhile, has to consider its regulatory obligations as well as the interests of its shareholders. A decision to list would involve significant changes to the company’s ownership structure and could bring its shares into public markets for the first time.

The disagreement has also extended to the appointment of Tata Sons chairman N Chandrasekaran. The company’s board has backed his continuation as chairman. Tata Trusts have raised objections to the process and the wider governance arrangements.

The issue has highlighted a larger question about how Tata Sons should be governed when its major stakeholders do not agree on important decisions.

Salve has argued that a company cannot operate effectively if its key stakeholders remain locked in a prolonged disagreement. He has also maintained that directors have a legal duty to act in the interests of the company rather than represent the interests of individual shareholders.

That principle could become important as the dispute develops. Tata Sons has a large and diverse portfolio, with stakes in businesses spanning information technology, automobiles, steel, aviation, consumer products and financial services.

The holding company owns significant interests in some of India’s biggest businesses. These include Tata Consultancy Services, Tata Motors, Tata Steel and Air India.

The value of Tata Sons therefore extends well beyond its own balance sheet. Decisions taken at the holding-company level can have implications for the wider Tata Group and its listed companies.

The proposed listing would also have implications for the Tata Trusts. A public offering could dilute their ownership depending on the structure and size of the issue. It could also introduce a much wider group of shareholders into the governance of Tata Sons.

The Tata Sons IPO has consequently become a sensitive issue. A listing could improve public disclosure and create a market value for the holding company. At the same time, it would mark a major change from the group’s traditional ownership model.

The Shapoorji Pallonji Group, which owns around 18.4% of Tata Sons, has supported the possibility of a listing. Its position adds another dimension to the shareholder discussions.

The Reserve Bank’s regulatory decision has now made the question more urgent. Tata Sons has also challenged the regulatory position, while the RBI has taken steps to protect its position in any potential legal proceedings.

The company therefore faces several issues at the same time — regulatory compliance, shareholder rights, board governance and the future ownership structure.

A final decision on the Tata Sons listing has not yet been announced. The company and its shareholders will need to consider the legal and regulatory requirements alongside the long-standing governance framework of the Tata Group.

The dispute is ultimately about more than an IPO. It raises questions about how one of India’s most influential business groups should balance its traditional trust-led ownership model with the demands of modern corporate governance and regulation.

As discussions continue, the Tata Group’s next steps will determine whether Tata Sons remains privately held or moves towards becoming a publicly traded company.


Categories
Leaders

Tata Trusts opposes Chandrasekaran’s fresh term

Tata Sons has approved a fresh five-year term for N Chandrasekaran as executive chairman, reversing his decision last month not to seek another term. The move has opened a new dispute with Tata Trusts, which has questioned the legality of the board decision.

The Tata Sons board voted 4-1 in favour of Chandrasekaran’s reappointment at its September 17 meeting. Noel N Tata, chairman of Tata Trusts and a Trusts nominee on the board, voted against the proposal.

Chandrasekaran’s current term ends on February 20, 2027. He had told the board on August 12 that he would not offer himself for another term. Tata Trusts accepted that decision and had called for a succession process to identify his replacement.

The situation changed after the Tata Sons Nomination and Remuneration Committee met on September 3. The committee asked Chandrasekaran to reconsider his decision and recommended his reappointment. He agreed to reconsider before Thursday’s board meeting, where directors approved the new five-year term by majority vote.

Tata Trusts has strongly objected to the reversal. Noel Tata said the chairman had already communicated his decision to step down and that the Trusts had accepted it. He argued that the company should now move ahead with the process of finding a successor rather than reopen the question of Chandrasekaran’s tenure.

The Trusts has also challenged the validity of Thursday’s board resolution. It described the decision as a “legal nullity”, arguing that the Tata Sons Articles of Association require the necessary support from Trusts nominee directors for the appointment or reappointment of the chairman. Noel Tata’s vote against the proposal is central to that argument.

Noel Tata also submitted a legal opinion from former Chief Justice of India D Y Chandrachud supporting the Trusts’ position, according to reports. The Trusts said the opinion was not properly considered by the board.

The dispute is significant because Tata Trusts collectively owns about 66% of Tata Sons, the holding company at the centre of the Tata Group. The next major step will be the company’s annual general meeting, where the board’s decisions will face shareholder approval.

The boardroom disagreement comes at another important moment for Tata Sons. The company has also decided to begin steps towards a possible stock market listing after the Reserve Bank of India rejected its request to surrender its registration as a Core Investment Company.

Tata Sons had sought deregistration after taking steps to meet debt-related requirements. The RBI’s decision has brought the listing requirement for an upper-layer non-banking financial company back into focus. The company said it would seek guidance from the RBI, Tata Trusts and other stakeholders on the compliance process.

The listing issue adds another layer to the disagreement between Tata Sons and Tata Trusts. A public listing would change the ownership and governance dynamics of the group’s holding company, which has stakes in major listed businesses including Tata Consultancy Services, Tata Motors and Tata Steel, besides controlling several unlisted businesses.

Chandrasekaran has led Tata Sons since 2017 and was given a second five-year term in 2022. During his tenure, the Tata Group expanded its presence in aviation, electronics, digital businesses and other emerging sectors. The group also completed the acquisition of Air India and has been pursuing major investments in manufacturing and technology.

His continuation was therefore expected to provide continuity as Tata Sons deals with regulatory requirements and large business projects. But the opposition from Tata Trusts means the question may now move beyond the boardroom.

The Trusts had already begun considering the succession process after Chandrasekaran’s August announcement. Its latest position indicates that it does not accept Thursday’s reversal as settling the matter.

The immediate focus will now shift to the Tata Sons AGM and the steps that follow. The board has backed Chandrasekaran, while Noel Tata and Tata Trusts have challenged that decision.

At the same time, Tata Sons is preparing to respond to the RBI’s position on its corporate structure and listing. The two developments together make the coming months important for the group’s leadership, governance and ownership structure.

What began as a planned leadership transition has now turned into a wider debate over chairman succession, shareholder rights and the future structure of Tata Sons. The final outcome will depend on the company’s shareholder process, regulatory requirements and how the dispute between the board and Tata Trusts develops.


Categories
Beyond

NSE Chief Chauhan denies Tata Sons chairman buzz

National Stock Exchange (NSE) Managing Director and CEO Ashishkumar Chauhan has rejected reports that he is being considered for the Tata Sons chairman post, calling the speculation baseless and factually incorrect.

The clarification came after reports emerged suggesting that Chauhan had emerged as a possible candidate in the succession race for Tata Sons Chairman N Chandrasekaran, whose current term ends in February 2027. NSE said the reports were not based on any information available with the exchange.

Chauhan also wrote to the exchange to deny the reports, saying the claims linking him to the Tata Sons position were speculative. He made it clear that his immediate focus remains on his responsibilities at NSE, particularly the exchange’s long-awaited initial public offering (IPO) and listing process.

The NSE chief said he was fully committed to working with the board and shareholders to complete the successful listing of the exchange. The statement comes at an important time for NSE, which is preparing for what could become one of India’s biggest market listings.

The speculation around Chauhan emerged after a report on the Tata Sons succession process named him alongside Tata Steel CEO T V Narendran and Tata Sons Chief Financial Officer Saurabh Agrawal as potential candidates. Chauhan was described as an external contender and a possible “dark horse” because of his experience in capital markets and financial services.

However, NSE has now clearly distanced its CEO from the Tata Sons succession discussion. The exchange said Chauhan had categorically denied the reports and reiterated his commitment to the institution he currently leads.

The timing is significant for NSE. The exchange has recently received regulatory clearance for its IPO after years of delays linked to regulatory and legal issues. The Securities and Exchange Board of India (SEBI) has given the exchange the go-ahead to proceed, paving the way for a potential listing later this month.

The NSE IPO is expected to attract substantial investor interest. The exchange is reportedly targeting a listing in the week beginning September 21, with the offering potentially valuing NSE at several billion dollars. Existing shareholders are expected to sell shares as part of the public offering rather than the exchange raising fresh capital.

The IPO represents a major milestone after years of regulatory hurdles, for Chauhan. NSE has been working towards a public listing since 2016, but investigations and litigation surrounding issues including its co-location system and access to trading infrastructure repeatedly delayed the process.

Recent legal developments have helped clear some of those obstacles. The Supreme Court dismissed a long-running SEBI case involving allegations related to preferential access to NSE systems, removing a significant legal hurdle ahead of the proposed listing.

Against this backdrop, leadership continuity at NSE has become particularly important. A change at the top while the exchange prepares for its IPO could have created additional uncertainty for investors and shareholders. Chauhan’s statement therefore reinforces the message that he remains focused on completing the listing process.

The NSE CEO has been closely associated with the development of India’s capital markets. He was among the founding team members of NSE and has held senior positions in the financial sector before returning to lead the exchange. His experience has been particularly relevant as NSE has expanded its role in India’s equity and derivatives markets.

The Tata Sons chairman succession, meanwhile, remains a closely watched issue in Indian corporate circles. Chandrasekaran’s decision not to seek a third term has triggered discussions about who will lead the Tata Group’s holding company from 2027. The eventual successor will oversee a conglomerate with businesses spanning technology, automobiles, steel, aviation, consumer products and financial services.

The search has reportedly included both internal and external names. T V Narendran, who heads Tata Steel, and Saurabh Agrawal, Tata Sons’ chief financial officer, have been among the names discussed. But there has been no official announcement identifying the next chairman.

The role is strategically important because Tata Sons sits at the centre of the Tata Group and holds significant stakes in several major Tata companies. The next chairman will also inherit responsibility for steering large investments and shaping the group’s long-term strategy.

Chauhan has sought to put the speculation surrounding his own name to rest. His message is that his attention remains firmly on NSE and its upcoming IPO.

With the exchange approaching a potentially historic public listing, the focus is now expected to shift back to the IPO process, regulatory preparations and investor interest. For Chauhan and NSE, delivering a smooth listing is likely to remain the immediate priority.

The Tata Sons succession process will continue separately, with the group expected to make a decision ahead of Chandrasekaran’s term ending in February 2027. Until then, Chauhan’s latest clarification makes one thing clear: he is not positioning himself as a candidate and remains committed to leading NSE through its next major chapter.


Categories
1 Minute-Read

Tata Trusts cleared in old share dispute

Tata Trusts has received relief in a decades-old dispute over 833 Tata Sons shares transferred to Naval Tata in 1989. The Maharashtra Charity Commissioner has closed the complaint, finding that the transaction followed the required process.

The shares were transferred from the Navajbai Ratan Tata Trust, with the trust receiving payment based on an approved valuation. The complaint was revived this year by trustee Vijay Singh, who sought an inquiry into the transaction.

The Commissioner also criticised aspects of Singh’s conduct while pursuing the case. The ruling comes as Tata Trusts, led by Noel Tata, faces growing attention over Tata Sons’ succession and governance.


Categories
Beyond

Tata Trusts gets relief in 1989 share transfer case

Tata Trusts has received relief in a nearly four-decade-old dispute involving the transfer of Tata Sons shares to former Tata Group chairman Naval Tata.

The Maharashtra Charity Commissioner has closed a complaint seeking an inquiry into the transfer of 833 Tata Sons shares from the Navajbai Ratan Tata Trust to Naval Tata in 1989. The Commissioner found that the transaction had followed the required process and that there was no need for further investigation.

The complaint had raised questions about whether the charitable trust was legally allowed to transfer the shares and whether the necessary procedures had been followed at the time.

The issue came back into focus this year after Vijay Singh, a trustee of the Navajbai Ratan Tata Trust and vice-chairman of Tata Trusts, sought an inquiry into the old transaction.

The Charity Commissioner has now rejected those concerns and closed the case.

According to the order, the share transfer was supported by the required documents. The trust received payment for the shares based on a valuation that had been accepted by the Commissioner of Wealth Tax.

The transaction was also included in the trust’s financial records. The trust had made a profit from the sale, according to the findings.

The shares were transferred in January 1989, when Naval Tata was an important figure in the Tata Group. The transaction involved the Navajbai Ratan Tata Trust, one of the charitable trusts that form the foundation of Tata Trusts.

The fact that the matter dates back to 1989 makes the case unusual. The Charity Commissioner had to examine records and decisions relating to a transaction that took place almost 40 years ago.

The Commissioner also criticised the way Vijay Singh handled the complaint. According to reports, Singh did not first share his complaint with the trust before submitting it to the Charity Commissioner.

The order also questioned certain aspects of his conduct as a trustee and criticised the manner in which the complaint was pursued.

For Tata Trusts, the decision comes at an important time. The organisation is playing a major role in discussions about the future leadership of the Tata Group.

Noel Tata, who heads Tata Trusts, has become an important figure in the group’s leadership and succession discussions. Tata Trusts has a controlling stake in Tata Sons, the main holding company of the Tata Group.

The question of who will lead Tata Sons next is also becoming more important. Tata Sons chairman N Chandrasekaran’s current term is scheduled to end in February 2027.

That has increased attention on the succession process and on the role Tata Trusts will play in choosing the next chairman.

The old share-transfer dispute had the potential to create additional questions around the governance of Tata Trusts. With the Charity Commissioner now closing the case, that issue has been removed from the immediate picture.

However, wider discussions about Tata Group succession and governance are expected to continue.

The Tata Group has grown significantly in recent years, with businesses spanning technology, automobiles, aviation, consumer products and other sectors. The appointment of the next Tata Sons chairman will therefore be closely watched.

Noel Tata’s position as chairman of Tata Trusts gives him an important role in the process. Since Tata Trusts owns a majority stake in Tata Sons, its views carry considerable weight in major decisions involving the holding company.

The Charity Commissioner’s decision also provides some clarity on the 1989 transaction. The regulator found that the transfer of the 833 shares was carried out according to the process applicable at the time.

Tata Trusts has welcomed the decision and rejected the allegations made against the trust. It has maintained that its actions have always been guided by its long-standing values and commitment to public service.

The dispute over the 1989 share transfer is closed. The focus at Bombay House is likely to return to the larger issues facing the Tata Group, particularly the succession process at Tata Sons.

The case is also a reminder that decisions made decades ago can come under fresh scrutiny when questions about ownership, governance and leadership emerge.

In this case, the Charity Commissioner’s ruling has cleared the old transaction and given Tata Trusts some breathing room.

But with the Tata Group preparing for its next leadership phase, attention will remain firmly on Noel Tata, Tata Trusts and the future of Tata Sons.


Categories
Leaders

Tata Sons chairman search delayed over trust approval

The search for the next Tata Sons chairman has hit a roadblock after the Sir Ratan Tata Trust (SRTT) was unable to nominate its representative to the panel tasked with finding Natarajan Chandrasekaran’s successor.

The delay comes more than two weeks after Chandrasekaran announced that he would not seek another term as chairman of Tata Sons. His current term is scheduled to end in February 2027, giving the Tata Group several months to complete the succession process. However, a regulatory restriction affecting the Sir Ratan Tata Trust has now slowed the exercise.

SRTT is one of the 13 charitable trusts that together form the majority shareholder in Tata Sons, the holding company of the Tata Group. The Tata Trusts collectively own about 66 per cent of Tata Sons, making their participation important in any major leadership decision involving the group.

The immediate problem is that SRTT is currently restricted from conducting its internal meetings because of an ongoing regulatory probe. Without being able to hold the necessary meeting, the trust cannot formally select and nominate its representative to the five-member joint search panel.

The Tata Trusts have now approached the Maharashtra Charity Commissioner seeking permission for SRTT to nominate its representative despite the restrictions. The decision of the Charity Commissioner is awaited. Until that approval comes through, the chairman succession process is unlikely to move ahead as planned.

The search panel was announced as part of the effort to identify Chandrasekaran’s successor. His decision not to continue as Tata Sons chairman came on August 12 and was unexpected, raising questions about the group’s succession planning and the transition at the top of one of India’s largest business conglomerates.

The delay is significant because the chairman of Tata Sons plays a central role in determining the broader strategic direction of the Tata Group. The group has businesses spanning automobiles, technology, steel, aviation, consumer products, financial services and other sectors. A leadership transition at the holding company therefore carries importance beyond the appointment itself.

The latest development also brings attention to the unusual ownership structure of Tata Sons. Unlike many large corporations, the company is controlled largely through charitable trusts. This structure has historically helped fund philanthropic activities while also giving the trusts substantial influence over the group’s corporate affairs.

The current regulatory hurdle has already affected Tata Sons in another way. The company’s annual general meeting was adjourned last month after it failed to achieve the required quorum. The absence of the necessary trust representation contributed to the difficulty in conducting the meeting. Tata Sons has since received a three-month extension from the Registrar of Companies to hold its AGM.

The next important date could be September 17, when the Tata Sons board is scheduled to meet. The board will be closely watched for developments on the chairman succession process as well as other matters arising from Chandrasekaran’s planned departure.

For now, Chandrasekaran remains legally entitled to continue as Tata Sons chairman until the end of his existing term in February. That provides some time for the group to resolve the issue, but the delay puts greater focus on how quickly the trusts and the company can complete the formal succession exercise.

The situation also puts attention on Noel Tata, chairman of Tata Trusts, as the group navigates the leadership transition. Any prolonged uncertainty could increase pressure on the Trusts to provide clarity to investors, regulators and other stakeholders about the group’s leadership plans.

The issue is particularly relevant as the Tata Group continues to play a major role in India’s manufacturing and technology ambitions. The conglomerate has been expanding its presence in areas such as electronics manufacturing, electric vehicles and other strategic industries. Stable leadership at Tata Sons will be important as these businesses move into their next phase of growth.

The succession question is therefore not simply about finding a replacement for Chandrasekaran. It also involves balancing the interests of Tata Sons, its board and the charitable trusts that control the company. The latest regulatory hurdle has brought that complicated relationship into sharper focus.

Neither Tata Sons nor Tata Trusts has so far issued an immediate public response to the latest reports. For the moment, the chairman succession process remains in limbo, with the Maharashtra Charity Commissioner’s decision emerging as a key step.

With Chandrasekaran’s term ending in February 2027, the Tata Group still has time to complete the transition. But the latest delay underlines the challenges involved in managing leadership succession within a corporate structure where charitable trusts hold significant ownership and influence.


Categories
Beyond

Tata Sons AGM faces quorum hurdle amid Trust dispute

The Tata Sons annual general meeting (AGM) scheduled for August 18 is facing a fresh procedural hurdle, with restrictions on the Sir Ratan Tata Trust (SRTT) raising serious questions over whether the meeting can meet the required quorum.

The issue comes at a particularly sensitive moment for the Tata Group. N Chandrasekaran, who has led Tata Sons since 2017, has decided not to seek reappointment when his current term ends on February 20, 2027. The Tata Trusts have begun the process of finding his successor, but the same regulatory restrictions affecting the AGM are also complicating the formation of the selection committee.

The immediate problem stems from an order by the Maharashtra Charity Commissioner restricting SRTT from convening trustee meetings. The directive was issued in May following complaints concerning the composition of the trust’s board and alleged non-compliance with provisions of the Maharashtra Public Trusts Act.

SRTT has sought relief from the Charity Commissioner, but the restrictions had not been lifted as of August 14. With the AGM only days away, the trust has little time to resolve the issue. It could also approach the Bombay High Court if regulatory relief does not come through.

SRTT and the Sir Dorabji Tata Trust (SDTT) are the two principal Tata trusts and together hold about 51.5% of Tata Sons. SRTT owns roughly 23.5%, while SDTT holds about 28%.

The problem is not simply that SRTT cannot attend the meeting. Under the Tata Sons Articles of Association, the two trusts have to jointly nominate a representative for the AGM. Article 86 sets out the quorum requirement and includes a jointly nominated representative of SDTT and SRTT.

Since SRTT cannot currently hold a trustee meeting, it cannot formally participate in that nomination process.

SDTT has now informed Tata Sons that the required quorum may not be available. Tata Sons, however, is expected to proceed with the AGM as scheduled. If the required quorum is not present, the meeting could be adjourned. The complication is that the adjourned meeting would still require the joint nominee, leaving the basic problem unresolved unless SRTT receives regulatory relief.

This has created an unusual situation for one of India’s most closely watched corporate groups. The AGM is not merely a routine annual meeting; it comes amid a leadership transition and could determine how quickly the Tata Group moves towards choosing Chandrasekaran’s successor.

The quorum dispute also affects Chandrasekaran’s immediate position.

Chandrasekaran is liable to retire by rotation as a director of Tata Sons. His continuation as chairman is legally linked to his position on the Tata Sons board. If the AGM cannot be validly constituted, however, officials familiar with the Articles of Association say he could continue as a director until a valid AGM is held, when his reappointment can be considered.

Chandrasekaran has already made clear that he does not intend to seek another term as chairman after February 2027. His decision followed months of uncertainty around his reappointment and differences within the Tata leadership structure.

That means the August 18 meeting could still be important even if it does not immediately settle the succession question. A delay could simply push the formal decision-making process further down the road.

The SRTT restrictions have created a second problem for Tata Sons: the selection committee for Chandrasekaran’s successor.

SDTT has already passed a resolution to initiate the setting up of a selection committee as soon as possible, in accordance with the Articles of Association of Tata Sons. The committee will recommend a candidate for appointment as the company’s next chairman.

However, the full process requires participation from both principal trusts. The two trusts are expected to jointly nominate three members to the selection committee.

With SRTT unable to hold a meeting, it cannot make the necessary nominations. As a result, SDTT’s resolution has started the process, but cannot by itself complete the succession mechanism.

The timing is significant. Chandrasekaran’s term ends in February 2027, giving Tata Sons roughly six months to complete the search, evaluate candidates and secure the necessary corporate approvals.

The Charity Commissioner’s action against SRTT is linked to an inquiry into the trust’s governance. The regulator directed the trust to postpone a May 16 meeting and refrain from convening similar meetings until an Inspector’s report is submitted.

The dispute also involves questions about the number of perpetual or life trustees on the SRTT board following changes to Maharashtra’s public trust law. The regulator has powers under Section 36A(1) of the Maharashtra Public Trusts Act to issue directions to a trust.

Separately, the Charity Commissioner’s office is examining allegations concerning the transfer of 833 Tata Sons shares in 1989 from the Navajbai Ratan Tata Trust to Naval H Tata. Former SRTT trustee Vijay Singh had sought an inquiry into the matter. Noel Tata, who is chairman of Tata Trusts and a trustee of the Navajbai Ratan Tata Trust, has denied the allegations, and the regulator is examining his response.

The restrictions have also affected the functioning of SRTT beyond Tata Sons. Accounts have reportedly not been finalised and grants of around ₹400 crore have been held up, while several decisions requiring trustee resolutions remain pending.

.

Categories
Leaders

N Chandrasekaran quits as Tata Sons chairman

N Chandrasekaran has resigned as chairman of Tata Sons, bringing a significant leadership transition to the Tata Group after nearly a decade at the helm of its holding company. Chandrasekaran, however, will continue in the position until the end of his current term on February 20, 2027, according to people familiar with the development and his statement.

The decision comes just days before the Tata Sons annual general meeting scheduled for August 18. The meeting had been expected to consider the reappointment of Chandrasekaran as a director, a key requirement for him to continue as chairman. His decision not to seek another term effectively removes that uncertainty and sets the stage for a leadership succession process at one of India’s most influential business groups.

In his communication to the Tata Sons board, Chandrasekaran said he would not offer himself for reappointment after his existing tenure ends. He also asked the board to begin the process of identifying his successor. The announcement marks the beginning of a transition rather than an immediate departure, allowing him to remain involved in the group’s affairs for several months.

The development follows weeks of uncertainty around Chandrasekaran’s position and the Tata Sons board. Earlier reports had said he was considering stepping down ahead of the August 18 AGM amid questions surrounding his reappointment and tensions within the Tata Trusts structure. Those reports had raised the possibility of an unexpected change at the top of the Tata Group.

Chandrasekaran’s exit is important because Tata Sons sits at the centre of the group’s sprawling business interests, with significant holdings and influence across information technology, automobiles, steel, power, consumer products, hotels, aviation and financial services. The chairman also plays a central role in determining the group’s long-term investment priorities and capital allocation.

His tenure has been marked by an aggressive expansion strategy. Under Chandrasekaran, the Tata Group pushed deeper into aviation following the acquisition and consolidation of Air India, while also increasing investments in semiconductors, electronics manufacturing, batteries, artificial intelligence and other emerging businesses.

The group has simultaneously worked to strengthen its position in traditional businesses while building new growth platforms. Tata Electronics has emerged as a major focus of the group’s semiconductor and electronics ambitions, while Tata Digital has been developed as a consumer technology platform. The group’s investments in battery manufacturing and defence-related capabilities have also formed part of its longer-term strategy.

Air India has been one of the most visible projects during Chandrasekaran’s tenure. The Tata Group has been attempting to rebuild the airline following its return to private ownership, with investments in aircraft, technology, operations and customer experience. Chandrasekaran recently described the transformation of Air India as a five-to-10-year effort, highlighting the scale of the challenge facing the group.

The leadership change comes even as Tata Sons remains financially strong. The company’s annual report for FY26 showed revenue rising 9.1% to Rs 42,367 crore, while profit after tax increased 21.8% to Rs 31,961 crore. The improvement was supported by investment gains and earnings from its portfolio of businesses.

At the broader Tata Group level, the business has continued to expand despite challenges in several large investments. The group reported aggregate FY26 revenue of about Rs 16.24 lakh crore, while profit after tax rose sharply during the year.

The financial performance, however, has existed alongside pressure in some of the group’s newer businesses. Air India recorded substantial losses, while Tata Digital, Tata Electronics and battery-related ventures have also required significant investment. Chandrasekaran has defended these businesses as long-term strategic bets rather than investments expected to generate immediate returns.

Markets reacted quickly to the news. Shares of several Tata Group companies came under pressure after the resignation announcement, with Tata Consultancy Services among the most closely watched stocks. TCS shares were reported to be down more than 3% during Wednesday’s trading session, while other Tata companies also declined. The market reaction reflected investor uncertainty surrounding the group’s future leadership and succession process.

Chandrasekaran joined the Tata Group nearly four decades ago and rose through its ranks before becoming chief executive of Tata Consultancy Services in 2009. He became chairman of Tata Sons in 2017, succeeding Ratan Tata in the role. His tenure has therefore covered a major period of transformation for the conglomerate, including the expansion of its global technology, automotive and aviation interests.

The immediate focus will now shift to succession planning, putting Tata Sons among the major Indian businesses undergoing senior leadership and succession changes. The board will have to identify a leader capable of managing both the group’s established businesses and its ambitious new investments. The next chairman will inherit a conglomerate with a strong financial base, but also major projects requiring sustained capital, execution and strategic patience.

For the Tata Group, the transition is therefore more than a change at the top. It will determine how the conglomerate balances its traditional businesses with its newer bets in technology, aviation, semiconductors, batteries and digital services. With Chandrasekaran remaining until February 2027, the group has several months to prepare for a carefully managed leadership handover.

Categories
Beyond

RBI keeps Tata Sons in upper layer

The Reserve Bank of India (RBI) has retained Tata Sons in the Upper Layer of non-banking financial companies (NBFCs) for 2026-27, keeping the long-running question over a possible stock-market listing of the Tata Group holding company alive.

The RBI’s latest classification brings Tata Sons under enhanced regulatory oversight at a time when the company is seeking to surrender its Core Investment Company (CIC) registration. The central bank has made it clear that Tata Sons’ inclusion in the upper layer does not prejudice its pending application for deregistration.

For Tata Sons, the development is significant because an NBFC-Upper Layer (NBFC-UL) classification generally carries a mandatory listing requirement. The company was first placed in the upper layer in 2022, and under the earlier framework it was expected to list within three years.

However, Tata Sons has been trying to avoid that outcome. It applied to the RBI in March 2024 to surrender its CIC registration and had repaid its debt as part of its efforts to move away from the regulatory conditions that could trigger a public listing. That application is still being examined.

The RBI changed the way upper-layer NBFCs are identified in June 2026. Under the revised scale-based regulation framework, an asset threshold of ₹1 lakh crore is now central to determining whether an NBFC falls into the upper layer.

Tata Sons is comfortably above that threshold. Its total assets stood at around ₹2.01 lakh crore as of March 31, 2026, making its inclusion under the revised framework difficult to avoid.

The new approach is more straightforward than the earlier system, which relied on a combination of size, interconnectedness, complexity and other risk parameters. The RBI’s latest framework puts greater emphasis on the scale of an NBFC, bringing several large public-sector financial institutions into the upper layer as well.

The RBI has expanded the FY27 upper-layer NBFC universe with the addition of major infrastructure financiers, including REC, Power Finance Corporation (PFC), Indian Railway Finance Corporation (IRFC) and HUDCO. The move reflects the central bank’s broader effort to bring large financial institutions under stronger regulatory supervision.

The immediate question is whether Tata Sons will ultimately have to list its shares on Indian stock exchanges.

The RBI has not given a fresh public deadline for a Tata Sons listing while its deregistration application remains under consideration. Reuters reported that the central bank is unlikely to insist on an immediate listing while the application is pending, although the regulatory position remains unresolved.

This leaves Tata Sons in an unusual position. It remains classified as an upper-layer NBFC, but at the same time its request to surrender its CIC licence is still before the RBI.

The uncertainty matters because a public listing would fundamentally change the ownership and governance dynamics of one of India’s most influential business groups.

Tata Trusts control about 66% of Tata Sons, through the Sir Ratan Tata Trust and Sir Dorabji Tata Trust. The Shapoorji Pallonji Group holds a significant minority stake and has been seeking ways to unlock value from its holding. A Tata Sons listing could potentially provide a market-based valuation and create a clearer exit route for the minority shareholder.

At the same time, a listing would bring greater public disclosure, shareholder scrutiny and market accountability to the holding company.

The RBI’s revised framework also makes the classification more consequential. Once an NBFC enters the upper layer, it remains subject to enhanced regulations for at least five years, even if it later falls below the eligibility threshold.

This means the latest classification cannot simply be viewed as a temporary consequence of Tata Sons’ asset size. The company would face a substantially tighter regulatory framework if it continues in the upper layer.

The broader objective is to strengthen governance, risk management and financial stability among India’s largest NBFCs. Upper-layer entities face stricter requirements because their size and interconnectedness could create wider risks for the financial system.

For Tata Sons and Tata Trusts, the RBI decision therefore leaves several possibilities open. The company can continue pursuing deregistration as a CIC, while preparing for the possibility that it may have to comply with the listing requirement.

The situation has also renewed attention on the internal debate around a potential Tata Sons IPO. Tata Trusts had resolved in July 2025 that Tata Sons should remain privately held, while some trustees have subsequently expressed support for a listing.

For the Shapoorji Pallonji Group, the issue has an added financial dimension because its Tata Sons stake has been used as collateral for borrowings. A public market valuation could potentially improve liquidity and provide greater flexibility around its investment.

For investors, the RBI’s decision is therefore more than another regulatory classification. It keeps the possibility of one of India’s biggest and most closely watched corporate listings firmly on the radar.

For now, however, Tata Sons remains private. The next major trigger will be the RBI’s decision on its deregistration application. Until that happens, the Tata Sons listing debate is likely to remain unresolved, with regulation, ownership, governance and value unlocking all pulling the company in different directions.