Categories
Beyond

RBI removes Paytm Payments Bank from bank list

The Reserve Bank of India (RBI) has formally removed Paytm Payments Bank Limited (PPBL) from the list of scheduled banks, completing another key step in the lender’s closure.

The RBI said Paytm Payments Bank has been excluded from the Second Schedule of the Reserve Bank of India Act, 1934. The exclusion was made through a notification dated July 31, 2026, which was subsequently published in the Gazette of India on September 7.

The development comes months after the central bank cancelled PPBL’s banking licence and the Delhi High Court ordered the winding up of the bank. The latest move is therefore largely part of the formal regulatory process surrounding the closure of Paytm Payments Bank.

The Delhi High Court, through orders passed in July, directed that PPBL be wound up under the Banking Regulation Act and the Companies Act. Girikumar M Nair, a former State Bank of India executive, was appointed as the Official Liquidator to oversee the process.

What led to the action

Paytm Payments Bank had been under RBI scrutiny for several years before its banking licence was cancelled.

In March 2022, the RBI stopped PPBL from onboarding new customers, citing material supervisory concerns. The bank was also directed to appoint an IT audit firm to conduct a comprehensive review of its information technology systems.

Further restrictions followed in January and February 2024. The RBI barred the bank from accepting fresh deposits, credits or top-ups in customer accounts, prepaid instruments and wallets. These restrictions significantly reduced the role of PPBL in Paytm’s digital payments ecosystem.

The RBI eventually cancelled the bank’s licence with effect from the close of business on April 24, 2026. At the time, the regulator said the affairs of PPBL had been conducted in a manner detrimental to the interests of the bank and its depositors and that the institution had not complied with conditions attached to its payments bank licence.

Paytm services continue

The latest RBI decision does not mean that Paytm as a company has stopped operating.

Paytm’s parent company, One97 Communications, had already separated its core payments business from Paytm Payments Bank after the regulatory restrictions began. Its UPI services now operate through a multi-bank model rather than depending on PPBL.

The Paytm app, UPI payments, QR-based merchant payments, Soundbox and other payment services continue to operate through banking partners. Paytm has previously said that its broader services would remain unaffected by action against the payments bank.

This distinction is important for customers. The RBI’s latest action concerns Paytm Payments Bank, not the entire Paytm platform.

Depositors and winding-up process

The closure of PPBL now moves into a more detailed liquidation phase. The RBI had said when cancelling the banking licence that the bank had sufficient liquidity to repay its entire deposit liability during the winding-up process.

The winding-up is expected to involve a large number of customers, creditors and other stakeholders. A Delhi High Court order in August noted that PPBL had more than 14 crore customers, including depositors and wallet holders, while also having more than 200 other creditors and vendors. EY Restructuring LLP was appointed as a process advisor to assist the Official Liquidator with the winding-up exercise.

The process involves verifying claims, managing depositor balances, protecting assets, settling creditors and handling regulatory and legal requirements.

Another setback for Paytm’s banking ambitions

The removal from the scheduled banks list marks the latest stage in the end of Paytm’s banking ambitions.

PPBL was once an important part of Paytm’s business model and digital payments ecosystem. Its regulatory troubles, however, forced Paytm to restructure its operations and build a payments model based on partnerships with other banks.

The latest development also had an immediate impact on investor sentiment. Shares of One97 Communications fell as much as 10% in early trading on October 8 following the RBI announcement.

For Paytm, the focus is now firmly on its fintech operations rather than running a banking subsidiary. The company’s ability to maintain customer confidence, expand UPI and merchant payments, and grow its financial services business will determine how effectively it moves beyond the long-running Paytm Payments Bank episode.

The RBI’s action also serves as a reminder of the importance of compliance and governance in India’s fast-growing fintech industry. What began as a regulatory intervention has ultimately resulted in the formal closure of one of the country’s most prominent payments banking ventures.
 

Categories
Beyond

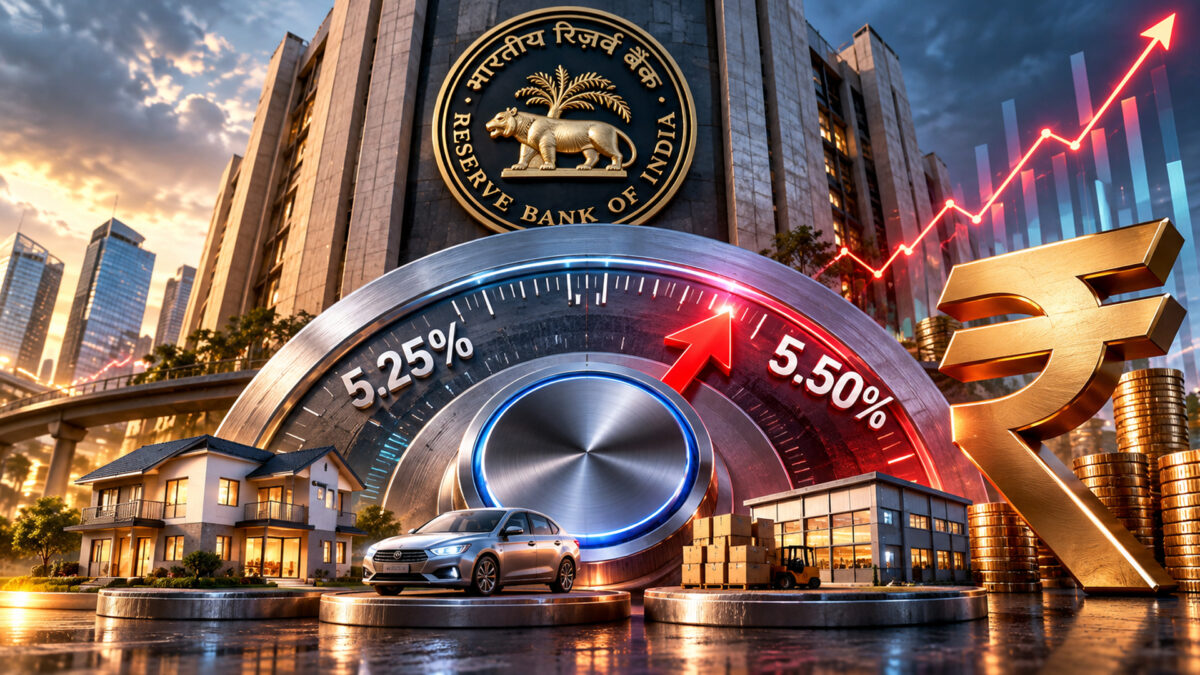
RBI hikes repo rate by 25 basis points

The Reserve Bank of India has raised the repo rate by 25 basis points to 5.50%, marking the first increase in the key policy rate since February 2023. The move is set to affect borrowing costs across the economy, with households, businesses and interest-rate sensitive sectors likely to feel the impact.

The decision by the Monetary Policy Committee (MPC) comes against a backdrop of renewed inflation concerns, higher crude oil prices and uncertainty in global markets. The central bank has also shifted its policy stance from “neutral” to “calibrated tightening”, signalling a greater focus on containing price pressures.

The most immediate impact will be felt by borrowers with floating-rate loans. Home loans linked to external benchmarks such as the repo rate are likely to become more expensive as lenders pass on the increase. New borrowers could also face higher interest rates as banks revise their lending rates.

The actual impact on a borrower’s monthly repayment will depend on the lender, loan benchmark, outstanding principal, existing interest rate and remaining tenure. A 25-basis-point increase may look modest, but even a small change can add considerably to the total repayment cost when applied to a large loan over several years.

A borrower with a ₹50 lakh home loan and 20 years remaining, for example, could see the monthly EMI rise by several hundred rupees if the full rate increase is passed through. The additional burden would be higher for someone with a ₹1 crore loan. The exact increase will vary depending on the existing rate and the lender’s reset mechanism.

Banks can respond to the rate increase in different ways. Some may raise the monthly EMI while keeping the repayment period unchanged. Others could keep the EMI broadly stable and extend the loan tenure. While the latter option may offer short-term relief, a longer tenure can increase the total interest paid over the lifetime of the loan.

Borrowers should therefore look beyond the EMI when assessing the impact of the rate hike. The revised interest rate, outstanding principal, remaining tenure and total interest payable will provide a clearer picture of the additional financial burden.

Existing fixed-rate borrowers are generally insulated from an immediate change in their loan rates. However, people seeking fresh fixed-rate loans or refinancing options could find borrowing costs less favourable as lenders adjust to the new interest-rate environment.

The effect will extend beyond housing. Auto loans and other floating-rate consumer loans could also become more expensive. Higher financing costs may make consumers more cautious about purchasing cars, two-wheelers and other high-value products, particularly if interest rates remain elevated for a prolonged period.

The stock market reaction has been mixed, reflecting the different ways sectors respond to higher rates. Banking shares have remained relatively resilient as investors assess the possibility of stronger lending yields.

Higher lending rates can support banks if loan rates rise faster than their funding costs, potentially improving net interest margins. The benefit, however, is not automatic. Banks may also have to pay more to attract deposits, particularly in a competitive environment where customers seek better returns on their savings.

The profitability impact will therefore depend on several factors, including loan growth, deposit costs, credit demand and asset quality.

Auto and real estate stocks face a different equation. The Nifty Auto index came under pressure as investors assessed the possibility of weaker vehicle demand resulting from higher financing costs. Automobiles, particularly two-wheelers and passenger vehicles, depend heavily on consumer credit.

Real estate companies are similarly sensitive to interest rates. Higher home-loan costs can affect housing affordability and cause potential buyers to postpone purchases. The impact could be more visible in segments where buyers are particularly dependent on mortgage financing.

Developers may also face higher borrowing costs when financing construction and expansion projects. This could influence project timelines, margins and new launches if rates remain high.

The latest policy decision also provides an important signal about the RBI’s approach to inflation. The move from a neutral stance to calibrated tightening suggests that the central bank is prepared to maintain tighter financial conditions if price pressures persist.

That shift could influence investor preferences. Companies with strong cash flows, manageable debt and resilient demand may be better placed to withstand a higher cost of capital. Highly leveraged businesses, meanwhile, could face greater pressure on profitability and expansion plans.

Despite the rate increase, the RBI remains confident about India’s growth prospects. The central bank has raised its FY27 growth forecast to 7.1%, indicating expectations of continued economic momentum even as monetary conditions become tighter.

The combination of strong growth and rising rates creates a mixed environment for businesses. Banks could gain from higher lending yields, while companies dependent on cheap credit may need to reassess investment and expansion plans. Consumers, meanwhile, may become more selective about large purchases.

The latest rate hike is also a reminder for home-loan borrowers to review their finances. Checking the revised interest rate, comparing refinancing options and considering partial prepayment can help reduce the long-term impact where financially feasible.

The key question now is whether the 25-basis-point increase will remain a one-time adjustment or become the beginning of a broader tightening cycle. Future decisions will depend largely on inflation, crude oil prices, global financial conditions and the strength of domestic demand.

Until those signals become clearer, borrowers and businesses will need to prepare for a financial environment where the era of steadily falling interest rates may be giving way to a period of higher borrowing costs.


Categories
Beyond

RBI set to consider first rate hike since 2023

The Reserve Bank of India (RBI) is widely expected to end its rate-cut cycle this week, with economists and bankers increasingly forecasting a 25-basis-point hike in the policy repo rate. The move would mark the first increase in the benchmark rate since February 2023, as rising crude oil prices, broadening inflation and a shift towards tighter monetary policy globally put pressure on the central bank.

The RBI’s Monetary Policy Committee (MPC) began its three-day meeting on Monday and is scheduled to announce its decision on Wednesday, October 7. The policy repo rate currently stands at 5.25%. A 25-basis-point increase would take it to 5.50%.

The expected move would represent a clear reversal from the easing cycle that began in February 2025. The RBI cut the repo rate by 25 basis points in February last year, followed by another 25-basis-point reduction in April, a 50-basis-point cut in June and a further 25-basis-point reduction in December. Those cuts brought the repo rate down from 6.50% to the current 5.25%.

The last rate hike came in February 2023, when the RBI raised the repo rate by 25 basis points to 6.50%. It subsequently kept the rate unchanged through 2023 and 2024 before beginning monetary easing in 2025.

A recent poll of 16 economists and bankers found that most expect the RBI to raise rates by 25 basis points in October. A separate Reuters poll of 61 economists showed 35, or nearly 60%, expecting a similar increase. Financial markets have been even more decisive, with interest-rate swaps pricing in a hike.

The biggest concern for the RBI is the changing inflation picture. India’s retail inflation rose to an eight-month high of 4.82% in August, from 4.45% in July. Inflation has remained above the RBI’s 4% medium-term target for three consecutive months, rising from 3.93% in May to 4.38% in June and 4.45% in July before the August increase.

Economists believe price pressures could become more widespread in the months ahead. Around 19% of the items in the consumer price index basket recorded inflation above 6% in August, compared with 13% in March, according to estimates cited by CareEdge Ratings. That suggests inflation is no longer limited to a few volatile categories.

Crude oil has emerged as another major risk. International oil prices have moved above $100 a barrel amid renewed tensions in West Asia. A prolonged period of expensive crude could push up petrol and diesel prices, raise transportation and production costs and eventually feed into consumer prices.

Higher energy costs are particularly important for India because the country relies heavily on imported crude oil. A sustained increase in oil prices can widen the import bill, put pressure on the current account and weaken the rupee. A softer rupee can, in turn, make imported commodities more expensive and add to inflationary pressures.

The global interest-rate environment has also changed. Major central banks have begun moving towards tighter policy as inflation risks have returned, while global bond yields remain elevated. Economists believe the RBI may need to narrow the interest-rate gap with other major economies and prevent financial conditions from becoming too loose.

The rupee‘s weakness is adding to that pressure. The currency has lost around 6% against the US dollar this year, according to recent market estimates. A rate hike could provide some support by making rupee-denominated assets relatively more attractive, although currency movements will continue to depend on global capital flows and the dollar’s strength.

At the same time, the RBI is not dealing with an economy that is losing momentum. Domestic growth has remained resilient, giving policymakers greater room to focus on inflation. The central bank had projected FY27 real GDP growth at 6.7%, but economists increasingly expect that forecast to be revised upwards following stronger-than-expected economic activity.

The first quarter of FY27 recorded GDP growth of 7.8%, supported by consumption, investment and exports. Healthy GST collections, automobile sales and bank credit have also pointed to continued economic activity. Some economists now expect the RBI to raise its full-year growth projection to above 7%.

That resilience is important because a rate hike carries a cost. Higher borrowing rates can increase EMIs on home, vehicle and personal loans, particularly for borrowers whose loans are linked directly to external benchmarks. Businesses could also face higher financing costs, potentially affecting investment decisions if monetary tightening continues for an extended period.

Banks, however, may not see a major immediate impact on credit demand. SBI Chairman C S Setty has said the economy remains resilient and that a possible repo rate increase may not materially affect credit growth. Banks could also adjust lending and deposit rates depending on liquidity and funding conditions.

Categories
Leaders

HDFC Bank appoints Anup Bagchi as new CEO

HDFC Bank has appointed Anup Bagchi as its new Managing Director and Chief Executive Officer, bringing an experienced ICICI Group veteran to the top job at India’s largest private sector lender.

The appointment, approved by the Reserve Bank of India (RBI), will be for three years from October 27, 2026, subject to shareholder approval. Bagchi will succeed Sashidhar Jagdishan, whose current term ends on October 26. He will join HDFC Bank as an additional director from October 2 and take over as MD and CEO the following month.

The leadership change marks an important moment for HDFC Bank. Bagchi is the first external candidate to be selected as the bank’s chief executive, breaking with a succession pattern that has largely favoured leaders from within the organisation.

At 56, Bagchi brings more than three decades of experience across banking, capital markets, wealth management and insurance. He has been associated with the ICICI Group since 1992 and has held senior positions across several businesses.

His career includes a stint as Executive Director at ICICI Bank from 2017 to 2023, where he oversaw retail, business and rural banking before moving to wholesale banking. He also held responsibilities spanning treasury, investment banking and digital financial services.

Bagchi later served as Managing Director and CEO of ICICI Securities for six years. Since June 2023, he has headed ICICI Prudential Life Insurance as its MD and CEO. He also served as chairman of ICICI Prudential Asset Management Company until May 2023 and held board positions within the wider ICICI Group.

His tenure at ICICI Prudential Life has also delivered measurable business growth. The insurer’s annualised premium equivalent rose 15% year-on-year to ₹10,407 crore in FY25, crossing the ₹10,000-crore mark for the first time. Profit after tax increased by nearly 40% to ₹1,189 crore during the year.

Bagchi is an alumnus of the Indian Institute of Technology Kanpur and the Indian Institute of Management Bangalore.

His move to HDFC Bank comes after a closely watched CEO succession process. Jagdishan, who took charge in October 2020 after succeeding banking veteran Aditya Puri, decided in August that he would not seek another term. His decision prompted HDFC Bank to accelerate its search for a successor.

The bank had submitted two names to the RBI for consideration, including Bagchi and HDFC Bank’s Deputy Managing Director Kaizad Bharucha. The central bank subsequently approved Bagchi’s appointment.

The new CEO will inherit a bank navigating several business and leadership challenges. HDFC Bank has been working through the longer-term impact of its merger with Housing Development Finance Corporation (HDFC), while also focusing on deposit mobilisation, retail growth and profitability.

The bank’s net interest margin (NIM), a closely watched measure of lending profitability, stood at 3.26% in the first quarter of FY27, down from 3.38% in the previous quarter. Its CASA ratio, which reflects low-cost current and savings deposits, also declined to 32.3% in Q1 FY27 from 34.1% in FY26.

Profit growth has also moderated. HDFC Bank reported a 5% year-on-year increase in net profit in the June quarter, according to Reuters. The bank’s leadership transition comes against this backdrop, along with concerns around investor confidence and the need to strengthen deposit growth.

Governance and leadership changes have added another layer to the transition. HDFC Bank chairman Atanu Chakraborty resigned in March, citing concerns about certain practices at the bank. A subsequent independent legal review commissioned by the bank found no evidence supporting those governance-related concerns.

Bagchi’s immediate priorities are therefore likely to extend beyond simply managing the leadership handover. Analysts have pointed to the need to accelerate retail and deposit growth, rebuild the CASA franchise, improve margins, strengthen technology and enhance communication with investors.

His experience across retail banking, wholesale banking, capital markets and insurance gives him exposure to several parts of the financial services ecosystem. His appointment also brings an external perspective at a time when HDFC Bank is seeking to sharpen its growth strategy and strengthen execution.

The transition will become official on October 27, when Bagchi takes charge from Jagdishan. His three-year term will run until October 26, 2029, under terms and remuneration approved by the RBI and subject to shareholder approval.

The change places a new face at the helm of HDFC Bank at a time when scale, profitability, deposit growth, technology and investor confidence are all central to the lender’s next phase.


Categories
Beyond

RBI tightens market-risk rules for banks

The Reserve Bank of India (RBI) has finalised new rules on how commercial banks must set aside capital to protect themselves against market-related losses, bringing India’s banking regulations closer to the revised Basel III framework.

The new rules will take effect from April 1, 2027, giving banks time to update their systems and prepare for the changes. The framework covers risks linked to interest rates, equity prices and foreign exchange movements.

One of the biggest changes is a clearer approach to the way banks classify financial instruments. The RBI has said instruments classified as “Held for Trading” will form part of the trading book for calculating capital requirements.

Banks will not be allowed to shift instruments between their trading and banking books simply to reduce the amount of capital they need to hold. If an instrument is moved, the bank will have to calculate its capital requirement before and after the change and maintain the difference where applicable.

The move is intended to prevent regulatory arbitrage and ensure that banks cannot use accounting classifications to lower their capital requirements without reducing the underlying market risk.

The RBI has prescribed the Simplified Standardised Approach for calculating risk-weighted assets for market risk. The framework broadly covers three areas: interest-rate risk, equity risk and foreign-exchange risk. Banks will also have to maintain the required market-risk capital on an ongoing basis, including at the close of each business day.

The rules also update the way banks calculate interest-rate risk. The RBI has revised the specific-risk tables to bring them in line with guidelines issued by the Basel Committee on Banking Supervision.

Foreign-exchange risk rules have also been updated. The new framework incorporates revised provisions for banks’ net open positions and forex risk capital charges. Certain eligible structural foreign-currency positions can also be excluded from the net open position calculation, subject to conditions set by the RBI.

Another change affects debt mutual funds and exchange-traded funds held in banks’ trading books. Their capital requirements will now be calculated with greater focus on the underlying risks of the instruments, while retaining safeguards prescribed by the regulator.

The RBI has also updated rules for positions protected through credit derivatives. The revised framework includes positions hedged through total return swaps where such transactions are allowed under the central bank’s credit-derivatives rules.

The final directions follow the RBI’s earlier draft framework and feedback received from stakeholders. The regulator said the revised rules are designed to align Indian regulations with Basel III while keeping implementation relatively simple and flexible for banks.

The RBI has already introduced transition measures. Intermediate transition scalars have been in place since April 1, 2024, to help banks gradually move towards the revised capital framework. The full set of directions will become applicable from April 1, 2027.

The new rules apply to commercial banks, while small finance banks, payments banks and local area banks are outside their scope.

Market risk becomes important when movements in interest rates, currency values, share prices or other financial markets affect the value of a bank’s investments and trading positions. Adequate capital acts as a buffer against such losses and helps protect a bank’s balance sheet.

The RBI’s revised framework therefore seeks to make the link between market risks and capital requirements clearer. Banks will need to review their trading portfolios, risk calculations, reporting systems and capital planning before the new rules take effect.

The changes also come as Indian banks increasingly operate across a wider range of financial markets. Stronger and more consistent capital requirements are intended to ensure that banks have enough financial protection when markets turn volatile.

With the April 2027 deadline now set, banks have several months to adjust to the revised Basel III market-risk framework and put the required systems in place.


Categories
Beyond

SEBI, RBI test tokenised corporate bonds in India

India has taken another step towards bringing blockchain technology into its financial markets with the launch of Demat 2.0, a pilot project by the Securities and Exchange Board of India (SEBI) to test tokenised corporate bonds.

The initiative, launched jointly with the Reserve Bank of India (RBI), aims to change how corporate bonds are issued, held, transferred and settled. Instead of relying entirely on conventional electronic records, the pilot uses Distributed Ledger Technology (DLT) to record ownership of bonds digitally. (sebi.gov.in)

The announcement was made by RBI Governor Sanjay Malhotra and SEBI Chairman Tuhin Kanta Pandey at the Global Fintech Fest in Mumbai. The project is being positioned as the next stage in India’s dematerialisation journey, building on the original demat system that changed the way investors held securities. (indianexpress.com)

Under the new system, a corporate bond is represented as a digital token on a distributed ledger. The ledger is maintained by regulated market infrastructure institutions, while ownership continues to remain within the regulated securities framework. This is different from cryptocurrencies, which operate outside India’s conventional securities market structure.

The pilot has already seen three corporate bond issuances worth a combined ₹1,025 crore from REC Ltd, Larsen & Toubro and IIFL. The L&T issue alone was worth ₹500 crore. The initial transactions are aimed at institutional investors as regulators test whether the technology can work smoothly at different stages of the bond lifecycle. (financialexpress.com)

One of the biggest changes under Demat 2.0 is the way transactions can be settled. The tokenised bond system is connected to the RBI’s wholesale Central Bank Digital Currency (CBDC) through the central bank’s Unified Market Interface (UMI).

This allows the bond and the payment to move together in what is known as atomic settlement or delivery-versus-payment. In simple terms, the buyer’s money and the seller’s security can be exchanged at the same time, reducing the possibility that one side of the transaction is completed while the other remains pending. (fortuneindia.com)

That could make the corporate bond market more efficient. Traditional transactions involve several stages of reconciliation between securities and cash records. A tokenised system can bring those records together, potentially reducing settlement time, operational work and counterparty risk.

The technology can also automate certain activities after a bond has been issued. Interest payments, redemptions and other asset-servicing functions can be handled through smart contracts, reducing the need for manual intervention. (financialexpress.com)

Importantly, tokenisation does not change the basic rights of investors. SEBI has said investors in tokenised corporate bonds will have the same rights as investors holding conventional bonds. The pilot is testing the technology and market infrastructure, rather than creating a separate class of securities with different investor protections. (livemint.com)

The pilot is initially focused on corporate bonds and institutional participants. Retail investors are not yet the main target, but regulators have indicated that wider participation could be considered as the system develops.

That could eventually be significant for India’s bond market. Tokenisation has the potential to make certain financial assets easier to divide and transfer, which could support fractional ownership and make high-value investments more accessible. However, moving from a controlled pilot to a broad retail system would require further testing, regulatory clarity and safeguards.

The project also involves several major financial-market institutions, including NSDL, CDSL, NSE, BSE, banks and NPCI. Their participation is important because Demat 2.0 needs to work across different parts of India’s existing financial infrastructure rather than operate as a standalone blockchain platform. (indianexpress.com)

The move comes as Indian regulators increasingly experiment with digital financial infrastructure. The RBI has been expanding the use cases for its digital rupee, while SEBI has been examining how emerging technologies can improve securities-market operations.

The central bank is also exploring the possibility of tokenising other assets, including gold, as it looks at expanding the Unified Market Interface. That suggests tokenisation could eventually move beyond corporate bonds if the underlying technology proves reliable. (economictimes.indiatimes.com)

There are still challenges. A pilot cannot establish how the system will perform during periods of heavy market activity or across a much larger number of investors. Questions around custody, taxation, accounting, secondary-market trading and operational risks will also need to be addressed before tokenised securities become widely used.

SEBI’s Demat 2.0 pilot is therefore less about replacing the existing demat system immediately and more about testing what the next generation of India’s securities infrastructure could look like.

If the experiment succeeds, corporate bonds could eventually move through a system where ownership, payment and post-trade services are connected digitally. That could make India’s debt market faster, more automated and easier to monitor while giving regulators a stronger technological foundation for the future.

The initiative marks a significant shift from simply holding securities electronically to creating a more integrated digital market infrastructure. For investors, the change may not be visible immediately, but the technology being tested could eventually reshape how corporate bonds, digital securities and other financial assets are issued and settled in India.


Categories
Beyond

FCNR-B inflows leave RBI managing liquidity

The Reserve Bank of India’s drive to bring more foreign currency into the country has produced a bigger response than expected. Now, the central bank is turning its attention to what comes next: managing the large amount of rupee liquidity created by the inflows and helping banks close their dollar-short positions.

Banks raised a substantial amount through Foreign Currency Non-Resident Bank, or FCNR-B, deposits under a special facility launched by the RBI. The programme was aimed at encouraging non-resident Indians and other eligible depositors to park foreign currency with Indian banks for longer periods.

The response was strong enough for the RBI to close the facility earlier than initially planned. By August 31, banks had mobilised around $127.23 billion through FCNR-B deposits, according to provisional data. When other foreign-currency borrowings are included, the total mobilisation was even higher.

The scale of the inflows has now created a new challenge for policymakers. The dollars that came into the banking system were converted and swapped into rupees, leaving banks with a significant amount of additional liquidity.

That means the RBI’s job has effectively moved from attracting foreign currency to managing its impact on domestic money markets.

The situation is particularly visible in the banking system, where surplus liquidity has climbed sharply. Banks are holding more funds than they immediately need, putting downward pressure on short-term interest rates. If the surplus remains elevated, the RBI may need to use its liquidity-management tools to prevent market rates from moving too far away from the policy rate.

The FCNR-B scheme was designed to address concerns around foreign exchange availability and the rupee. The RBI offered banks a special dollar-rupee swap arrangement, making it more attractive for them to mobilise FCNR-B deposits with maturities of three to five years.

The arrangement provided access to foreign currency funding. For the RBI, it helped bring dollars into the financial system at a time when the rupee was facing pressure from global uncertainties.

The latest developments show just how effective the scheme was.

ICICI Bank alone mobilised about $17.88 billion through FCNR-B deposits. The lender offered competitive rates for large deposits and subsequently deployed a portion of the funds through its overseas operations and other international financing activities.

The bank also used part of its foreign currency resources for lending and standby letters of credit, while raising additional funds through dollar-denominated bonds in overseas markets.

ICICI Bank’s experience illustrates how Indian lenders can use the foreign currency raised through the scheme rather than simply keeping the funds idle.

However, the bigger issue for RBI is the effect on the rupee and domestic liquidity.

When banks receive dollars and enter into swaps with the central bank, the transactions have an impact on the amount of rupees circulating in the financial system. With the FCNR-B response much stronger than anticipated, the resulting liquidity surplus has become significant.

This is where dollar-short positions could become important.

Banks that have received foreign currency and entered into currency swaps need to manage their positions as the transactions mature or are unwound. The RBI could use these flows as part of its broader foreign exchange and liquidity management strategy.

The central bank will have to strike a careful balance. It needs to ensure that the rupee does not come under unnecessary pressure while also preventing excess liquidity from distorting short-term interest rates.


Categories
Beyond

India retail inflation rises to 4.45% in July

India’s retail inflation rose to 4.45% in July, marking a second consecutive month above the Reserve Bank of India’s (RBI) 4% medium-term target and pointing to renewed pressure on household budgets. The latest Consumer Price Index (CPI) reading was higher than the 4.38% recorded in June, with food prices emerging as the main driver of the increase.

The July inflation figure, released by the Ministry of Statistics and Programme Implementation (MoSPI), remains comfortably within the RBI’s broader tolerance band of 2% to 6%. However, it is the highest reading recorded under the new 2024-base-year CPI series, making the latest data important for policymakers as they assess the direction of prices and interest rates.

For ordinary households, the biggest concern continues to be food inflation. The Consumer Food Price Index (CFPI) rose to 5.52% in July from 5.32% in June. The increase was linked to higher prices of several food items, including ginger, garlic and onions. Tomato prices, however, moved in the opposite direction and helped limit the overall rise in food prices.

The latest numbers also show a noticeable difference between rural and urban consumers. Rural inflation increased to 4.84% in July, while urban inflation stood at 3.96%. The gap suggests that price pressures remain more pronounced in rural India, where food and essential commodities account for a larger share of household spending.

The government data showed that the rise in headline inflation was not limited to food. Higher prices were also recorded in categories such as personal care and social protection, restaurants and accommodation services, food and beverages, and intoxicants. Among individual items, precious-metal jewellery, including silver, gold, diamond and platinum jewellery, recorded some of the highest inflation rates.

At the other end of the scale, some products recorded relatively low inflation or price declines. Potato, motor cars and jeeps, lady’s finger, peas and tomatoes were among the items with lower inflation rates in July. The mixed movement across individual products highlights how changes in prices are affecting different sections of the consumer basket in different ways.

The July data also puts the spotlight on the monsoon. Reuters reported that weaker rainfall contributed to higher prices of ginger, garlic and onions. A recovery in rainfall could help improve supplies and ease food inflation in the coming months. At the same time, weather-related risks remain an important factor for the inflation outlook, particularly because agricultural supply has a direct impact on food prices.

Energy prices are another concern. India remains heavily dependent on imported crude oil, making domestic inflation sensitive to movements in international energy markets. Reuters reported that global crude prices remained elevated in July despite a temporary easing in the conflict-related pressure on oil markets. Domestic fuel prices did not undergo significant additional changes during the month, limiting the immediate impact on consumers.

Transport inflation nevertheless edged higher to 4.43% in July from 4.31% in June. This matters because transport costs can eventually feed into the prices of goods and services by raising logistics and distribution expenses. Any sustained increase in fuel and transportation costs could therefore create wider inflationary pressure.

The latest inflation reading is unlikely to immediately change the RBI’s interest-rate stance. The central bank kept its benchmark policy rate unchanged at its latest meeting, choosing to wait for clearer evidence on whether price pressures were becoming broad-based. Since the July CPI reading remains within the RBI’s 2%-6% tolerance range, economists do not expect an immediate rate hike.

Still, policymakers will be watching the trend closely. Reuters cited economists who expect inflation to move above 5% from September if price pressures persist. One estimate pointed to the possibility of a 25-basis-point rate hike in December if inflation becomes more persistent and begins influencing expectations.

Core inflation, which excludes volatile food and fuel prices, was estimated at 3.9% in July. That figure is significant because it suggests that underlying price pressures remain more contained than the headline CPI number indicates. India does not publish an official core inflation measure; economists calculate it using detailed CPI data.

The RBI has already revised its inflation outlook for 2026-27, cutting its headline inflation forecast by 10 basis points to 5%. The central bank will now have to balance the need to support economic growth with the risk that higher food, fuel and service prices could keep inflation above its 4% target for longer.

Categories
Beyond

RBI keeps Tata Sons in upper layer

The Reserve Bank of India (RBI) has retained Tata Sons in the Upper Layer of non-banking financial companies (NBFCs) for 2026-27, keeping the long-running question over a possible stock-market listing of the Tata Group holding company alive.

The RBI’s latest classification brings Tata Sons under enhanced regulatory oversight at a time when the company is seeking to surrender its Core Investment Company (CIC) registration. The central bank has made it clear that Tata Sons’ inclusion in the upper layer does not prejudice its pending application for deregistration.

For Tata Sons, the development is significant because an NBFC-Upper Layer (NBFC-UL) classification generally carries a mandatory listing requirement. The company was first placed in the upper layer in 2022, and under the earlier framework it was expected to list within three years.

However, Tata Sons has been trying to avoid that outcome. It applied to the RBI in March 2024 to surrender its CIC registration and had repaid its debt as part of its efforts to move away from the regulatory conditions that could trigger a public listing. That application is still being examined.

The RBI changed the way upper-layer NBFCs are identified in June 2026. Under the revised scale-based regulation framework, an asset threshold of ₹1 lakh crore is now central to determining whether an NBFC falls into the upper layer.

Tata Sons is comfortably above that threshold. Its total assets stood at around ₹2.01 lakh crore as of March 31, 2026, making its inclusion under the revised framework difficult to avoid.

The new approach is more straightforward than the earlier system, which relied on a combination of size, interconnectedness, complexity and other risk parameters. The RBI’s latest framework puts greater emphasis on the scale of an NBFC, bringing several large public-sector financial institutions into the upper layer as well.

The RBI has expanded the FY27 upper-layer NBFC universe with the addition of major infrastructure financiers, including REC, Power Finance Corporation (PFC), Indian Railway Finance Corporation (IRFC) and HUDCO. The move reflects the central bank’s broader effort to bring large financial institutions under stronger regulatory supervision.

The immediate question is whether Tata Sons will ultimately have to list its shares on Indian stock exchanges.

The RBI has not given a fresh public deadline for a Tata Sons listing while its deregistration application remains under consideration. Reuters reported that the central bank is unlikely to insist on an immediate listing while the application is pending, although the regulatory position remains unresolved.

This leaves Tata Sons in an unusual position. It remains classified as an upper-layer NBFC, but at the same time its request to surrender its CIC licence is still before the RBI.

The uncertainty matters because a public listing would fundamentally change the ownership and governance dynamics of one of India’s most influential business groups.

Tata Trusts control about 66% of Tata Sons, through the Sir Ratan Tata Trust and Sir Dorabji Tata Trust. The Shapoorji Pallonji Group holds a significant minority stake and has been seeking ways to unlock value from its holding. A Tata Sons listing could potentially provide a market-based valuation and create a clearer exit route for the minority shareholder.

At the same time, a listing would bring greater public disclosure, shareholder scrutiny and market accountability to the holding company.

The RBI’s revised framework also makes the classification more consequential. Once an NBFC enters the upper layer, it remains subject to enhanced regulations for at least five years, even if it later falls below the eligibility threshold.

This means the latest classification cannot simply be viewed as a temporary consequence of Tata Sons’ asset size. The company would face a substantially tighter regulatory framework if it continues in the upper layer.

The broader objective is to strengthen governance, risk management and financial stability among India’s largest NBFCs. Upper-layer entities face stricter requirements because their size and interconnectedness could create wider risks for the financial system.

For Tata Sons and Tata Trusts, the RBI decision therefore leaves several possibilities open. The company can continue pursuing deregistration as a CIC, while preparing for the possibility that it may have to comply with the listing requirement.

The situation has also renewed attention on the internal debate around a potential Tata Sons IPO. Tata Trusts had resolved in July 2025 that Tata Sons should remain privately held, while some trustees have subsequently expressed support for a listing.

For the Shapoorji Pallonji Group, the issue has an added financial dimension because its Tata Sons stake has been used as collateral for borrowings. A public market valuation could potentially improve liquidity and provide greater flexibility around its investment.

For investors, the RBI’s decision is therefore more than another regulatory classification. It keeps the possibility of one of India’s biggest and most closely watched corporate listings firmly on the radar.

For now, however, Tata Sons remains private. The next major trigger will be the RBI’s decision on its deregistration application. Until that happens, the Tata Sons listing debate is likely to remain unresolved, with regulation, ownership, governance and value unlocking all pulling the company in different directions.

Categories
Beyond

RBI targets early FY28 for plastic notes rollout

India is moving closer to introducing plastic currency, with Reserve Bank of India (RBI) Governor Sanjay Malhotra saying the central bank is targeting the circulation of polymer banknotes from the beginning of the next financial year. If the ongoing field trials and operational preparations go as planned, Indians could start seeing polymer ₹10 and ₹20 notes from early FY28, which begins in April 2027.

The announcement marks a significant step in India’s long-running plan to introduce polymer currency. The RBI has been examining the possibility of using plastic-based notes for years, but the latest update suggests that the proposal has now moved beyond an initial assessment and into a structured testing phase.

Speaking to reporters after the RBI’s monetary policy announcement on Wednesday, Malhotra said the central bank would first evaluate the results of the ongoing pilot before making a final decision on wider circulation. The RBI does not want to rush the transition and will test how the new banknotes perform in real-world Indian conditions.

The initial trial will focus on the ₹10 and ₹20 denominations. The government has approved the RBI’s proposal to conduct field trials involving one billion polymer notes of each denomination, taking the total to two billion notes. The exercise will allow the central bank to examine durability, performance, printing efficiency, security and how easily the notes can be handled in everyday transactions.

The choice of ₹10 and ₹20 notes is deliberate. These are among the most frequently handled denominations in the Indian currency system and tend to wear out faster because they change hands repeatedly. According to the latest information, the two denominations together account for nearly 25% of the total volume of banknotes in circulation, while representing only around 1.4% of the total value. This gives the RBI an opportunity to conduct a large-scale test without exposing the currency system to significant financial risk.

Polymer banknotes are made from a thin, flexible plastic material instead of traditional cotton-based paper. Their biggest advantage is durability. They are more resistant to moisture, dirt and tearing and can remain usable for much longer than conventional paper currency. This could be particularly useful for low-value notes, which are frequently damaged and withdrawn from circulation.

For the RBI, longer-lasting currency could also mean fewer notes needing to be replaced. That could eventually reduce the cost and logistical burden associated with printing, transporting and withdrawing worn-out banknotes. However, the central bank will have to establish whether those advantages hold up under India’s varied climate and heavy cash usage before deciding on a wider rollout.

Security is another important part of the experiment. Polymer currency can accommodate features such as transparent windows and other anti-counterfeiting elements that are difficult to reproduce. The RBI will therefore examine whether polymer notes can provide stronger protection against counterfeit currency while remaining easy for the public and banks to authenticate.

The initial introduction is also designed to minimise disruption to India’s cash infrastructure. ₹10 and ₹20 notes are mainly distributed through bank branches rather than ATMs, allowing the RBI to test the new currency without immediately requiring major changes to ATM networks. A move to polymer notes in higher denominations could be more complicated because existing machines may need software upgrades, recalibration or other modifications to recognise and process the new notes.

Importantly, the arrival of polymer currency will not mean that India’s existing paper notes suddenly become invalid. The government has clarified that there is currently no proposal to completely replace paper banknotes. If the pilot succeeds, polymer notes are expected to circulate alongside conventional currency.

India’s move towards plastic money is not entirely new. The RBI has explored polymer currency for more than a decade. Earlier trials and proposals were considered in select cities, including Mysore and Cochin, while a separate proposal discussed in 2009 was eventually shelved because of technical challenges. The latest programme therefore represents another attempt to determine whether polymer banknotes can work effectively on a much larger scale in India.

The current approach is cautious. Rather than immediately replacing paper currency, the RBI will first put millions of polymer notes through real-world use. Their durability, security, public acceptance, printing process and overall performance will be closely assessed. The experience will then help determine whether polymer banknotes should be introduced in other denominations.

If the ₹10 and ₹20 trials are successful, the RBI could eventually consider extending polymer currency to higher-value denominations such as ₹100 and ₹500. But that decision is still some distance away and will depend on the results of the pilot.

For ordinary Indians, the change may initially seem small — a ₹10 or ₹20 note that feels different in the hand. But behind that simple change is a larger attempt to modernise India’s currency management system, make banknotes last longer and reduce the constant cycle of replacing worn-out cash.

For now, the key date to watch is April 2027, when the RBI is targeting the beginning of circulation of polymer notes, provided the trials and preparations remain on track.