Categories
Beyond

NPCI clears confusion over new UPI charges

The National Payments Corporation of India (NPCI) has clarified that the upcoming 18% Goods and Services Tax (GST) on the Merchant Discount Rate (MDR) will not make most UPI payments more expensive for small merchants.

The clarification came after reports raised concerns that GST on UPI transactions above ₹2,000 could increase the cost of digital payments for small shopkeepers, vendors and other businesses.

NPCI said the 18% GST will not be charged on the full value of a UPI payment. It will apply only to the MDR, which is a payment-processing fee charged on certain merchant transactions. The new MDR framework will take effect from October 15.

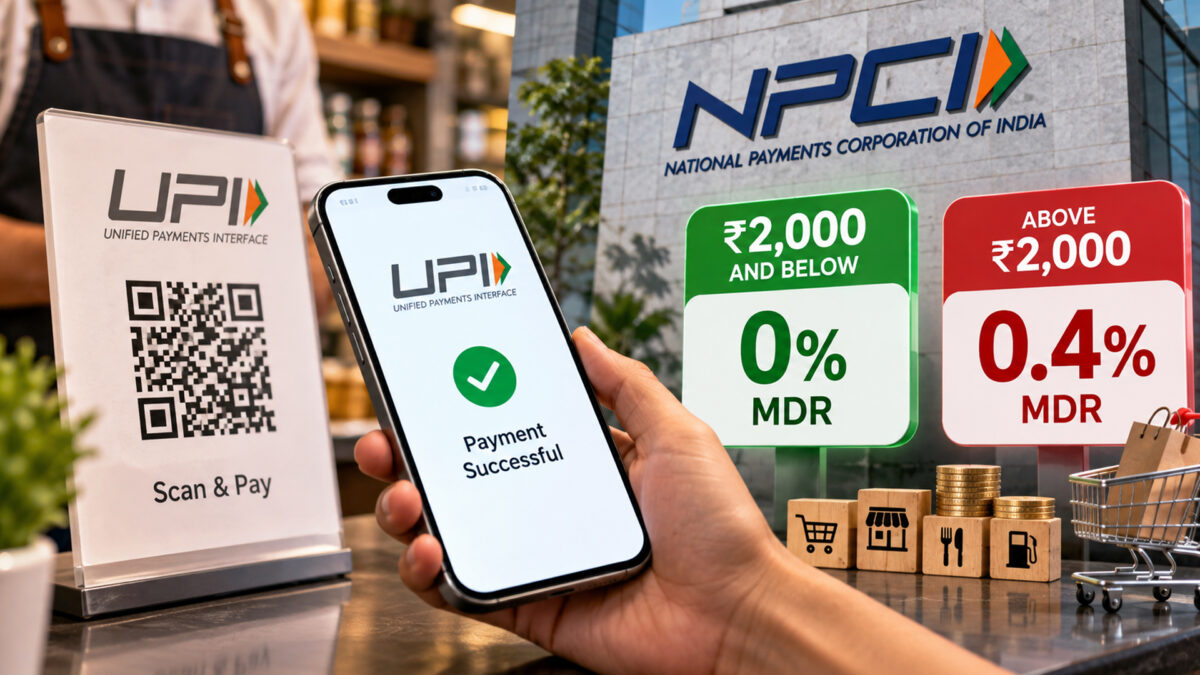
Under the revised rules, a 0.4% MDR will apply to specified person-to-merchant (P2M) UPI transactions above ₹2,000. The fee will be capped at ₹300 for transactions of ₹75,000 and above. The merchant, rather than the customer, bears the MDR.

The key point for everyday UPI users is that payments of up to ₹2,000 will continue to have zero MDR. NPCI said more than 96% of UPI merchant transactions fall within this limit, meaning the vast majority of transactions will remain outside the new MDR framework.

Person-to-person UPI transfers will also remain completely free, regardless of the amount being transferred. Payments to eligible small merchants covered under the zero-MDR framework will continue without the fee as well.

The GST calculation is another important distinction.

If a customer makes a ₹10,000 UPI payment to a merchant, the 0.4% MDR would amount to ₹40. The 18% GST would then be calculated on the ₹40 MDR, which comes to ₹7.20. The GST is therefore not 18% of the ₹10,000 transaction.

In effect, the merchant’s total payment-processing cost would be ₹47.20 in this example, subject to the applicable rules. The customer should not be charged an additional UPI fee simply because the payment is above ₹2,000.

GST-registered businesses can also claim input tax credit on the GST paid on MDR, subject to the normal GST rules. This allows eligible businesses to adjust the tax paid on the payment-processing service against their output tax liability.

NPCI said merchants receiving up to ₹1 lakh a month through UPI will not be liable to pay MDR. This exemption is intended to protect smaller businesses and keep low-value digital payments affordable.

There is, however, a narrower group of merchants that has prompted questions. Some businesses may have annual turnover below the GST registration threshold but receive more than ₹1 lakh a month through UPI. Such merchants may not qualify for the small-merchant MDR exemption and may also be unable to claim input tax credit if they are not registered under GST.

The issue has attracted attention because UPI has become a major part of India’s retail payment system. From roadside vendors and neighbourhood shops to restaurants and large retailers, businesses increasingly depend on QR-code payments.

The new MDR framework marks a shift from the long-standing zero-MDR model for UPI. The government and NPCI have said the change is intended to create a revenue stream for the digital payments ecosystem while protecting small-value transactions.

MDR is not a government tax. It is a fee distributed among participants in the payments ecosystem, including banks and payment service providers, to support the operation and expansion of UPI.

The government has also maintained that the new structure will not affect ordinary consumers using UPI. The change is focused on selected merchant payments rather than person-to-person transfers.

Some industry groups and businesses, however, have raised concerns about the additional cost for merchants handling larger UPI transactions. Retailers and payment-intensive businesses have questioned whether even a small fee could affect businesses operating on thin margins.

The distinction between the transaction value and the MDR is therefore central to the latest debate. A ₹5,000 or ₹10,000 UPI payment does not attract an 18% GST on its entire value. The tax applies only to the MDR charged on an eligible merchant transaction.

The new rules will also introduce different MDR rates for certain categories. Specified sectors such as railways, telecom services, insurance and fuel will have a concessional flat MDR of ₹5 on eligible transactions above ₹2,000.

For consumers, the immediate takeaway is simple: UPI remains free for person-to-person transfers, payments up to ₹2,000 and eligible small merchants. The new charge mainly affects specified higher-value merchant transactions from October 15.

NPCI’s latest clarification is aimed at clearing confusion before the new UPI MDR system takes effect. While the framework introduces a new cost for some merchants, the regulator says the impact will remain limited for most small businesses and everyday digital payments.
 

Categories
Corporate

Fintechs oppose NPCI’s default UPI plan

India’s digital payments ecosystem is witnessing fresh tensions as several fintech companies have raised strong objections to a proposed NPCI feature that would allow users to complete Unified Payments Interface (UPI) transactions using a pre-selected default payment app with a single click. Smaller payment firms argue that while the move promises greater convenience, it could significantly strengthen the dominance of market leaders such as PhonePe and Google Pay, making it harder for smaller players to compete.

The proposal, currently being evaluated by the National Payments Corporation of India (NPCI), is part of a broader initiative to simplify UPI payments by reducing the number of steps required during online checkouts. Under the plan, users would choose a preferred UPI app once, and future transactions on participating merchant platforms would automatically open that app instead of displaying a list of available payment applications.

Several fintech companies have urged NPCI to reconsider the proposal, warning that it could reshape India’s highly competitive digital payments market in favour of the biggest platforms. According to industry executives, most smartphone users are unlikely to change their default payment app once it is set. As a result, larger apps with an established customer base could attract an even bigger share of transactions, leaving smaller UPI applications with fewer opportunities to acquire or retain users.

Industry participants believe the proposal may unintentionally create a “winner takes most” environment. They argue that the current UPI checkout process, which allows users to choose from multiple payment apps for every transaction, encourages healthy competition by giving all apps equal visibility. Removing that choice at the payment stage, they say, could gradually reduce traffic to emerging fintech platforms.

Companies opposing the proposal include smaller UPI service providers and payment startups that have written to NPCI, expressing concerns over its potential impact on innovation and market diversity. They have suggested that instead of introducing a permanent default option, NPCI should preserve user choice or explore alternative methods that do not favour larger players.

The issue comes at a time when PhonePe and Google Pay together account for the overwhelming majority of UPI transactions in India. According to industry data, the two platforms collectively process more than 80 per cent of all UPI payments, while the remaining market is shared among Paytm, Cred, Amazon Pay, Navi, Super.money and several other payment apps. Smaller firms fear the proposed feature could widen this gap even further.

Supporters of the proposal, however, argue that it would improve the user experience by making digital payments faster and more seamless. A one-click checkout could reduce transaction time, eliminate the need to select an app repeatedly and lower the chances of users abandoning purchases during the payment process. Merchants are also expected to benefit from quicker checkouts and potentially higher payment completion rates.

NPCI has reportedly described the feature as an optional convenience rather than a mandatory system. Users would still be able to change their preferred payment app whenever they wish. However, critics believe that in practice, very few customers regularly revisit default settings, meaning early market leaders would enjoy a lasting advantage.

The debate highlights a broader challenge facing India’s rapidly expanding digital payments ecosystem: balancing innovation with fair competition. UPI has become the backbone of the country’s digital economy, processing billions of transactions every month across online shopping, bill payments, peer-to-peer transfers and merchant payments. Any change to the payment flow therefore has far-reaching implications for consumers, merchants and fintech companies alike.

Industry experts say maintaining an open and competitive UPI ecosystem has been one of the key reasons behind its remarkable success. Since its launch, UPI has enabled both established companies and startups to build innovative payment solutions on a common platform. Many fintech firms now worry that reducing visibility for smaller apps could discourage future innovation and investment.

NPCI has not announced a final decision on the proposal and is understood to be reviewing feedback received from stakeholders across the payments industry. The organisation is expected to hold further consultations before deciding whether and how the feature should be rolled out.

For consumers, the proposal presents a trade-off between convenience and choice. While faster one-click payments could simplify everyday transactions, industry players believe preserving a level playing field is equally important to ensure continued innovation, competitive pricing and better digital payment services. As India’s UPI ecosystem continues to evolve, the outcome of the discussions could shape the future of the country’s digital payments landscape for years to come.

Also Read: Google’s Gemini surges to 950 mn monthly users

Categories
Technology

Jumpp enters UPI arena after NPCI greenlight

Indian fintech platform Jumpp has taken a major step in its growth journey after receiving approval from the National Payments Corporation of India (NPCI) to offer Unified Payments Interface (UPI) services directly through its app. The move allows users to make everyday digital payments while managing their investments and financial planning from a single platform.

Founded by Sarvjeet Singh Virk, Jumpp started as an AI-driven financial platform focused on helping users access investment products such as digital gold, mutual funds and systematic investment plans (SIPs). With the addition of UPI services, the company is expanding its role from a wealth-management app to a broader financial services platform.

Users will now be able to carry out peer-to-peer transfers, merchant payments, utility bill payments and mobile recharges without leaving the Jumpp app. The company says the integration is aimed at reducing the need to switch between multiple applications for different financial activities.

To support the new payment offering, Jumpp has partnered with YES Bank for banking infrastructure and Bharat Bill Payment System (BBPS) services. The platform also uses the Account Aggregator framework, enabling users to view and manage financial information from different accounts in one place.

The NPCI approval marks an important milestone for the startup as competition intensifies in India’s rapidly growing digital payments market. NPCI, which oversees UPI and other retail payment systems in the country, grants approval to third-party application providers that meet regulatory and operational requirements.

Jumpp believes the combination of AI-powered financial guidance and digital payments can help users make smarter financial decisions while simplifying day-to-day money management. The company is particularly focused on expanding access to digital financial services in Tier II and Tier III cities, where demand for integrated financial solutions continues to grow.

As digital payments become increasingly central to daily life, Jumpp’s entry into the UPI ecosystem signals its ambition to become a one-stop platform for spending, saving, investing and managing money across India.

Also Read: India may stay away from sugar exports

Categories
1 Minute-Read

NPCI rolls out UPI wallet for Global AI Summit visitors

The National Payments Corporation of India (NPCI) has introduced its UPI One World wallet service for international attendees of the India AI Impact Summit 2026 in New Delhi.

Visitors from over 40 countries can make seamless, real-time payments across India without needing an Indian bank account or mobile number. Funds can be loaded via international debit or credit cards, and payments can be made by scanning standard UPI QR codes.

The service is active at Delhi airport and the summit’s NPCI pavilion, simplifying transactions for global delegates.