Categories
Beyond

NPCI clears confusion over new UPI charges

The National Payments Corporation of India (NPCI) has clarified that the upcoming 18% Goods and Services Tax (GST) on the Merchant Discount Rate (MDR) will not make most UPI payments more expensive for small merchants.

The clarification came after reports raised concerns that GST on UPI transactions above ₹2,000 could increase the cost of digital payments for small shopkeepers, vendors and other businesses.

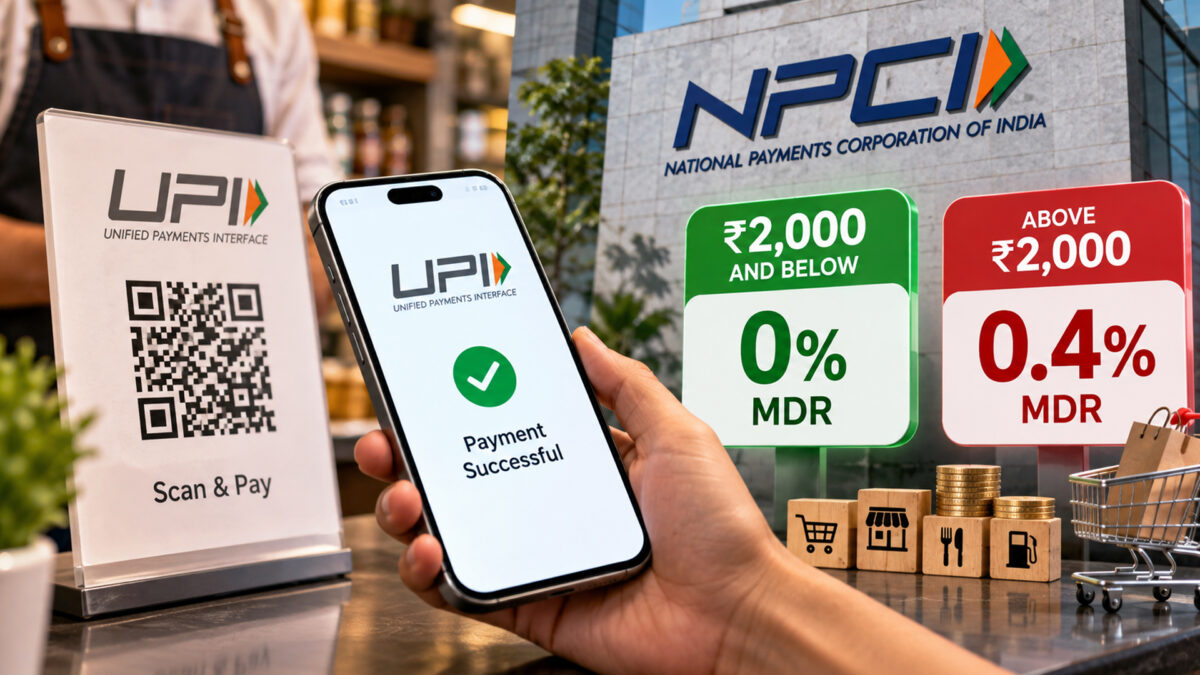
NPCI said the 18% GST will not be charged on the full value of a UPI payment. It will apply only to the MDR, which is a payment-processing fee charged on certain merchant transactions. The new MDR framework will take effect from October 15.

Under the revised rules, a 0.4% MDR will apply to specified person-to-merchant (P2M) UPI transactions above ₹2,000. The fee will be capped at ₹300 for transactions of ₹75,000 and above. The merchant, rather than the customer, bears the MDR.

The key point for everyday UPI users is that payments of up to ₹2,000 will continue to have zero MDR. NPCI said more than 96% of UPI merchant transactions fall within this limit, meaning the vast majority of transactions will remain outside the new MDR framework.

Person-to-person UPI transfers will also remain completely free, regardless of the amount being transferred. Payments to eligible small merchants covered under the zero-MDR framework will continue without the fee as well.

The GST calculation is another important distinction.

If a customer makes a ₹10,000 UPI payment to a merchant, the 0.4% MDR would amount to ₹40. The 18% GST would then be calculated on the ₹40 MDR, which comes to ₹7.20. The GST is therefore not 18% of the ₹10,000 transaction.

In effect, the merchant’s total payment-processing cost would be ₹47.20 in this example, subject to the applicable rules. The customer should not be charged an additional UPI fee simply because the payment is above ₹2,000.

GST-registered businesses can also claim input tax credit on the GST paid on MDR, subject to the normal GST rules. This allows eligible businesses to adjust the tax paid on the payment-processing service against their output tax liability.

NPCI said merchants receiving up to ₹1 lakh a month through UPI will not be liable to pay MDR. This exemption is intended to protect smaller businesses and keep low-value digital payments affordable.

There is, however, a narrower group of merchants that has prompted questions. Some businesses may have annual turnover below the GST registration threshold but receive more than ₹1 lakh a month through UPI. Such merchants may not qualify for the small-merchant MDR exemption and may also be unable to claim input tax credit if they are not registered under GST.

The issue has attracted attention because UPI has become a major part of India’s retail payment system. From roadside vendors and neighbourhood shops to restaurants and large retailers, businesses increasingly depend on QR-code payments.

The new MDR framework marks a shift from the long-standing zero-MDR model for UPI. The government and NPCI have said the change is intended to create a revenue stream for the digital payments ecosystem while protecting small-value transactions.

MDR is not a government tax. It is a fee distributed among participants in the payments ecosystem, including banks and payment service providers, to support the operation and expansion of UPI.

The government has also maintained that the new structure will not affect ordinary consumers using UPI. The change is focused on selected merchant payments rather than person-to-person transfers.

Some industry groups and businesses, however, have raised concerns about the additional cost for merchants handling larger UPI transactions. Retailers and payment-intensive businesses have questioned whether even a small fee could affect businesses operating on thin margins.

The distinction between the transaction value and the MDR is therefore central to the latest debate. A ₹5,000 or ₹10,000 UPI payment does not attract an 18% GST on its entire value. The tax applies only to the MDR charged on an eligible merchant transaction.

The new rules will also introduce different MDR rates for certain categories. Specified sectors such as railways, telecom services, insurance and fuel will have a concessional flat MDR of ₹5 on eligible transactions above ₹2,000.

For consumers, the immediate takeaway is simple: UPI remains free for person-to-person transfers, payments up to ₹2,000 and eligible small merchants. The new charge mainly affects specified higher-value merchant transactions from October 15.

NPCI’s latest clarification is aimed at clearing confusion before the new UPI MDR system takes effect. While the framework introduces a new cost for some merchants, the regulator says the impact will remain limited for most small businesses and everyday digital payments.
 

Categories
Beyond

UPI MDR bill opens door to charges

India’s popular Unified Payments Interface (UPI) could eventually have a new revenue model after the Finance Ministry introduced a Bill in Parliament seeking to amend the Payment and Settlement Systems Act, 2007. The proposed changes would give the government the power to decide which electronic payment modes can attract a Merchant Discount Rate (MDR) and which should remain exempt.

For millions of Indians who use UPI every day, however, there is no immediate reason to worry about an extra charge. The Bill itself does not impose MDR on UPI transactions or introduce a fee for customers. UPI payments will continue to remain free under the existing system until the government issues separate notifications specifying any future charges.

At present, Section 10A of the Payment and Settlement Systems Act provides a statutory exemption from charges for notified payment modes, including UPI and RuPay debit cards. The proposed amendment seeks to remove this blanket exemption.

Instead, the government would be able to notify, from time to time, which digital payment modes should continue with zero MDR and which could attract merchant charges. It would also have the flexibility to determine the applicable rates, transaction categories and entities responsible for paying them.

In simple terms, the government is not charging for UPI today. It is creating the legal framework that could allow such charges in the future.

Merchant Discount Rate is a fee paid by a merchant to banks, payment aggregators or payment service providers for processing a digital transaction. When a customer pays a shopkeeper using a payment method that carries MDR, the merchant does not necessarily receive the entire transaction amount. A small portion can be deducted as the processing fee and shared among participants in the payments ecosystem.

UPI has operated differently. Since January 2020, the government has mandated zero MDR on UPI and RuPay debit card transactions to encourage digital payments. Merchants currently receive the full value of UPI transactions, while banks and payment companies depend partly on government incentives to cover processing costs.

The Finance Ministry’s Bill does not introduce a customer transaction fee. If MDR is introduced later, it would initially be a charge on merchants rather than UPI users.

However, that does not necessarily mean consumers would never feel its impact. Businesses could choose to absorb the additional cost, negotiate lower margins or potentially factor the cost into their pricing. The actual effect would depend on the structure eventually notified by the government.

This is why the current development is better understood as a policy change enabling future MDR, rather than an immediate return of UPI charges.

The scale of India’s digital payments ecosystem has changed dramatically since UPI was launched. According to a Parliamentary Standing Committee on Finance report released in March 2026, around 88% of India’s digital transactions are now conducted through UPI.

Banks and payment service providers process more than 23 billion UPI transactions every month, with the total value approaching ₹30 lakh crore. UPI transactions have continued to set records as more consumers and businesses shift towards digital payments.

The rapid growth has also increased the cost of maintaining the payments infrastructure. The parliamentary panel warned that the zero-MDR model could become financially unsustainable as UPI expands further.

The committee estimated that UPI could add another 600 million users and eventually handle between 100 billion and 150 billion transactions every month. Such growth would require continued investment in technology, infrastructure, cybersecurity and payment processing.

Payment companies have been pushing for a change to the zero-MDR system for some time.

The Payments Council of India had earlier urged the government to reconsider the policy, arguing that incentives provided to the digital payments ecosystem cover only a fraction of the estimated cost of maintaining and expanding UPI services.

The industry body had proposed a limited MDR structure, including a 0.3% charge on UPI transactions involving large merchants. The idea was to create a revenue stream without making everyday low-value digital payments expensive.

The latest Bill gives the government room to consider such a calibrated approach in the future.

NPCI data showed that UPI transactions touched about ₹29.88 lakh crore in July 2026, while transaction volume reached 23.66 billion. The July transaction value was around 19% higher than the same month a year earlier.

That growth explains the government’s focus on building a financially sustainable digital payments ecosystem. UPI has become deeply embedded in everyday life, from buying groceries and paying utility bills to making large purchases and transferring money between bank accounts.

If Parliament approves the amendment, the next step will be government notifications specifying whether MDR will apply, which payment modes or transactions will be covered, what rates will be charged and who will bear the cost.

For now, users can continue making UPI payments without worrying about a new transaction fee. The proposed amendment simply changes who has the power to decide the future of MDR.