Categories
Corporate

Sensex crashes 1,050 points, Nifty slips below 23,900

Indian stock markets witnessed a sharp selloff on Monday upon opening, as rising global crude oil prices, geopolitical tensions in West Asia, and persistent foreign investor outflows rattled investor confidence. The BSE Sensex plunged over 1,050 points during intraday trade, while the NSE Nifty50 slipped below the crucial 23,900 mark.

The decline came after international crude oil prices surged past the $100-per-barrel level following uncertainty surrounding US-Iran negotiations. Since India depends heavily on oil imports, the spike in crude prices raised concerns over inflation, fiscal pressure, and economic growth.

Market heavyweight Reliance Industries came under strong selling pressure due to worries over rising input costs and weaker consumer sentiment. Banking stocks including HDFC Bank and ICICI Bank also dragged the indices lower as investors turned cautious amid global uncertainty. Aviation shares, particularly IndiGo parent InterGlobe Aviation, declined sharply as higher fuel prices threatened profitability.

Auto and consumer stocks remained under pressure throughout the session, reflecting fears that inflationary trends could weaken demand. Broader market sentiment also stayed negative, with midcap and smallcap stocks witnessing widespread selling.

However, oil exploration and energy companies bucked the trend. ONGC and Oil India traded higher as rising crude prices are expected to improve their revenue outlook. Select defensive sectors such as utilities and energy also showed relative resilience amid the broader market weakness.

Foreign institutional investors continued their selling streak, adding pressure on the rupee, which weakened further against the US dollar. Analysts believe continued volatility in global energy markets and geopolitical developments could keep Indian equities under stress in the near term.

Also Read: Palki Sharma starts a digital media global news platform
Categories
Leaders

Palki Sharma starts a digital media global news platform
Senior journalist Palki Sharma has launched a new digital-first media platform called India Global Review, marking a new phase in her journalism career after her exit from Firstpost.

The platform, also known as IGR, will focus mainly on international news, geopolitics and global developments. According to Sharma, the idea behind the venture is to present world events with deeper context and from an Indian point of view.

India Global Review is expected to produce digital video content, analysis programmes and global news coverage for audiences in India and abroad. Reports said the platform plans to expand its reach across regions including the United States, Europe, West Asia and Africa.

Speaking about the launch, Sharma said modern audiences are looking for clear, factual and balanced reporting at a time when global news is becoming increasingly fast-paced and polarised. She added that IGR aims to simplify complex international developments for viewers.

Over the years, Sharma has built a strong following through her coverage of global affairs and geopolitical issues. She previously worked with WION and later Firstpost, where her news shows gained large online audiences.

The company has reportedly started building editorial and production teams as part of its expansion plans. Reports also said the platform has received investor backing to support its operations and future growth.

With more audiences consuming news through mobile phones, streaming platforms and social media, several journalists are now building direct digital media brands.

The launch of India Global Review also comes at a time when global news coverage is seeing rising demand among Indian audiences interested in international politics, business and diplomacy.

Media analysts say Sharma’s experience in international reporting and her strong digital presence could help the platform build a significant audience quickly.

Also Read: Kalyan Jewellers Q4 profit climbs up to ₹410 cr

Categories
Corporate

Titan Q4 profit shoots up by 35% to ₹1,179 cr

Titan Company has reported a strong performance for the fourth quarter of FY26, with its consolidated net profit rising 35% year-on-year to ₹1,179 crore, compared to ₹871 crore in the same quarter last year. The growth was primarily driven by strong demand in its jewellery business, which remains the company’s largest revenue contributor.

The Tata Group company also posted a sharp 46% increase in total income, which climbed to around ₹20,300 crore from ₹13,891 crore in the corresponding period of the previous year. The strong top-line growth reflects healthy consumer demand, particularly for gold jewellery and premium products across key markets.

According to the company’s earnings update, the jewellery segment continued to lead overall performance, benefiting from steady customer demand and festive as well as wedding-related purchases. Higher gold prices did not significantly dampen demand, as consumers shifted preferences toward lighter designs and investment-oriented purchases such as gold coins.

The watches and eyewear segments also contributed positively, though jewellery remained the key growth driver for the quarter. The company’s retail expansion strategy, both in India and overseas, further supported sales momentum during the period.

Despite strong revenue growth, the company operates in an environment of rising input costs, particularly due to elevated gold prices. However, efficient product mix management and strong brand positioning helped sustain profitability.

The results highlight Titan’s continued dominance in India’s organised jewellery market, led by its flagship brand Tanishq. The company also continues to benefit from increasing consumer preference for branded jewellery over unorganised players.

Also Read: Lenskart shares slide after ₹5,316 cr block deal

Categories
Leaders

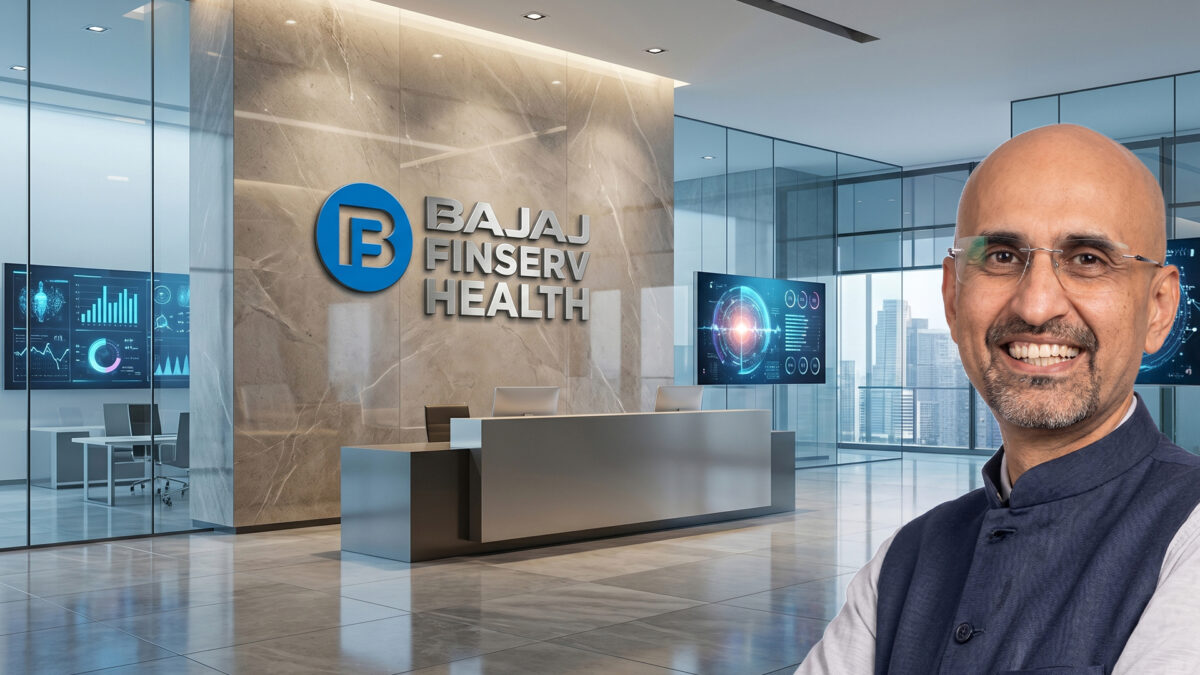
Deepak J. Matai named CEO of Bajaj Finserv Health

Bajaj Finserv Health has appointed Deepak J. Matai as its new Chief Executive Officer, strengthening the company’s leadership as it expands its digital healthcare business in India.

Matai brings over two decades of experience in the healthcare and pharmaceutical sectors and is expected to lead the company’s next phase of growth, product expansion, and technology-driven healthcare services. Before joining Bajaj Finserv Health, he held leadership roles across healthcare, diagnostics, and pharmaceutical businesses, gaining experience in strategy, operations, and digital transformation.

The company said the appointment comes at a time when digital healthcare adoption is growing rapidly in India, driven by increasing demand for online consultations, preventive healthcare, insurance-linked wellness services, and digital medical platforms.

Bajaj Finserv Health operates a digital healthcare ecosystem that connects users with doctors, diagnostic services, pharmacies, and wellness products through a single platform. The company has been focusing on expanding its healthcare offerings by integrating insurance, technology, and preventive care solutions.

Commenting on the appointment, the company said Matai’s industry expertise and leadership experience would help strengthen its long-term healthcare vision and improve customer-focused services. The platform aims to further scale its digital health infrastructure and enhance accessibility for users across urban and semi-urban markets.

With Deepak Matai taking charge as CEO, Bajaj Finserv Health is expected to accelerate its expansion plans and strengthen its position in the country’s fast-growing health-tech industry.

The healthcare technology market in India has seen significant growth in recent years, with rising smartphone penetration and growing awareness around digital medical services. Companies are increasingly focusing on creating end-to-end healthcare platforms combining consultations, diagnostics, insurance, and wellness management.

Also Read: Anthropic CEO says firm grew 80-fold with AI boom

Categories
Technology

Google Pixel phones get major May update

Google has released its May 2026 update for Pixel smartphones, focusing mainly on fixing bugs and improving device performance ahead of the expected Android 17 rollout.

The update resolves a number of common issues faced by Pixel users. These include wireless charging slowdowns, display flickering and screen freezing problems reported on several models.

Google has also fixed a camera bug affecting some Pixel 10 devices, where the camera app would freeze during video recording or while switching zoom levels.

Apart from these fixes, the update includes the latest Android security patch and general stability improvements designed to make devices run more smoothly.

For Pixel 10 users, Google has added a security-related anti-rollback feature that blocks phones from returning to older Android versions after updating. The feature is aimed at improving system security and reducing software-related risks.

The update is being rolled out gradually to supported Pixel devices worldwide. Users can download it manually by checking the software update section in phone settings.

Reports describe the May update as a preparation step for Android 17, helping reduce compatibility issues before the major software release arrives later this year.

Also Read: Meesho Q4 loss narrows 88% to ₹166 cr

Categories
Leaders

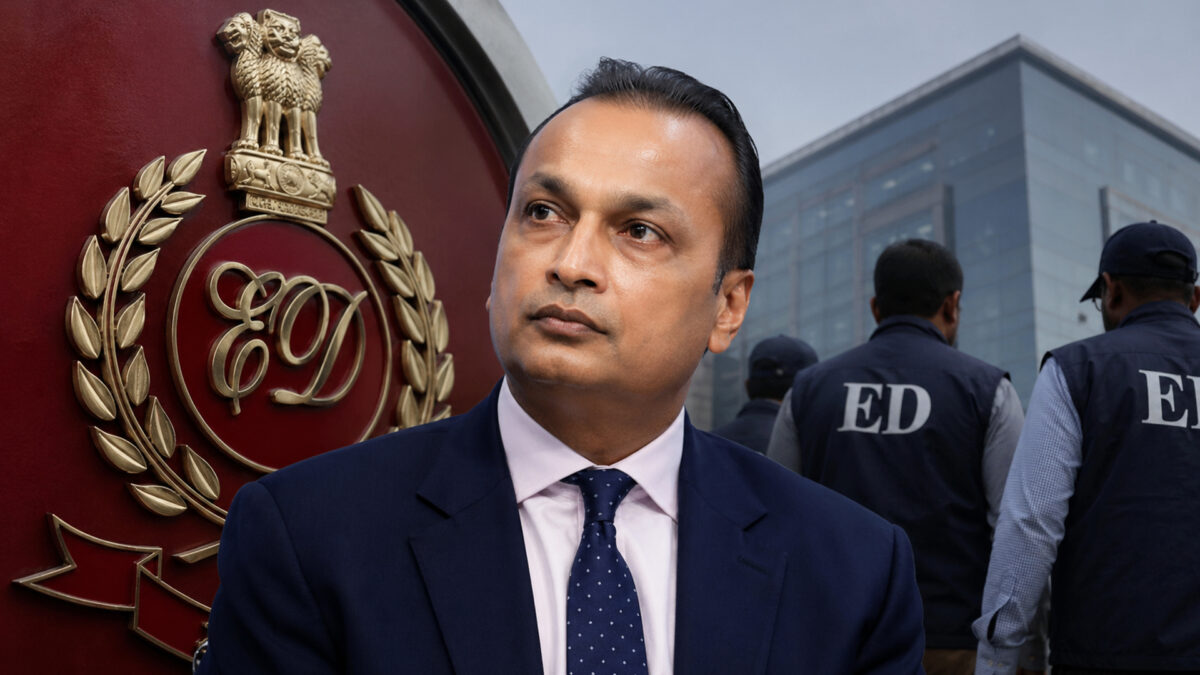
Anil Ambani files defamation case against NDTV

Reliance Group Chairman Anil Ambani has filed a defamation case in the Delhi High Court against NDTV over its reports on ongoing CBI and Enforcement Directorate investigations involving companies linked to his business group.

Ambani told the court that NDTV published around 72 reports in recent months that damaged his reputation and business image. His lawyers claimed the reports were unfair and presented allegations as facts.

During the hearing, Ambani’s legal team also alleged that the Adani Group, is interested in companies linked to the Reliance ADA Group. The lawyers argued that the NDTV reports were part of a targeted campaign against him.

The Delhi High Court issued notices to NDTV, its parent company AMG Media Networks, and NDTV CEO and Editor-in-Chief Rahul Kanwal, asking them to respond to the allegations. However, the court did not pass any immediate order and will hear the matter again in July.

Ambani’s lawyers said many reports directly used his name even though the investigations were against certain group companies and not him personally. They argued this created a negative public perception and harmed his image.

The suit seeks damages of more than ₹2 crore. Ambani has told the court that any compensation awarded in the case will be donated to charity.

The reports under dispute are linked to investigations by the CBI and ED into alleged financial irregularities involving Reliance Group companies.

The Delhi High Court is expected to hear the matter in detail during the next hearing scheduled for July 18.

NDTV has not yet publicly responded to the lawsuit.

Also Read: Julius Baer names Kunal Sumaya as interim India Head

Categories
1 Minute-Read

Coforge profit more than doubles to ₹612 cr in Q4

IT services firm Coforge posted a strong set of results for the fourth quarter, with its net profit more than doubling to ₹612 crore, marking a 144% jump compared to the same period last year. The company’s performance was supported by healthy deal wins and steady demand from global clients.

Revenue also grew 30% year-on-year to ₹4,450 crore, driven mainly by strong business in key international markets, especially the Americas. Coforge said new contracts and consistent execution helped boost overall momentum during the quarter.

The company remains optimistic as demand for digital transformation services continues to support growth.

Categories
Beyond

Reliance Jamnagar refinery units shut for upkeep

Reliance Industries is preparing to temporarily shut down certain processing units at its massive 660,000 barrels-per-day refinery for scheduled maintenance, according to a senior government official. The shutdown is expected to last around three to four weeks and will take place later this month.

The maintenance will include a crude distillation unit as well as several secondary processing units at the refinery. The facility is part of Reliance’s Jamnagar complex in Gujarat, one of the largest and most advanced refining hubs in the world.

Officials said the shutdown is planned after Nayara Energy resumes operations at its own refinery later in the month. This sequencing is intended to ensure smooth fuel supply across the domestic market and avoid any disruption during the maintenance period.

The maintenance activity is described as routine upkeep, aimed at ensuring operational efficiency and reliability of the refinery units. Sources indicated that the shutdown is part of planned maintenance cycles that large-scale refineries typically undergo.

Reliance operates one of the world’s biggest refining complexes, processing large volumes of crude oil into fuels and petrochemical products for both domestic consumption and exports. The Jamnagar site is a key contributor to India’s fuel supply chain.

According to officials, the shutdown is not related to any operational failure or emergency situation. Instead, it is a scheduled activity aligned with broader refinery management planning.

The timing of the maintenance is also coordinated with market conditions and other refinery operations in India. This helps maintain balance in fuel availability while large units undergo servicing.

Reliance has not issued an official public statement on the development. However, government sources confirmed that the plan has been discussed within the petroleum ministry framework.

The refinery’s maintenance is expected to conclude within three to four weeks, after which normal operations will resume.

Also Read: Vi names Kumar Mangalam Birla as non-executive Chairman

Categories
Corporate

NCLAT upholds Adani bid, rejects Vedanta appeal

India’s corporate insolvency process for Jaiprakash Associates Ltd (JAL) saw a key development as the National Company Law Appellate Tribunal (NCLAT) upheld the selection of Adani Enterprises as the winning bidder, while dismissing challenges raised by Vedanta Ltd.

The tribunal rejected Vedanta’s petitions against the Committee of Creditors’ decision, which had approved Adani’s resolution plan for the debt-laden company. The NCLAT observed that there was “no merit” in the objections raised and declined to interfere with the lenders’ commercial judgment.

The case relates to the insolvency resolution of Jaiprakash Associates Ltd, a heavily indebted conglomerate with interests across infrastructure, real estate, and cement. Under the Insolvency and Bankruptcy Code, creditors evaluated competing bids to determine the best recovery option.

Adani’s resolution plan, valued at around ₹14,500 crore, had already been approved by the Committee of Creditors. Vedanta had also submitted a competing bid, which it argued was higher in value and more beneficial for lenders. However, the lenders chose Adani’s proposal, citing overall feasibility and structure of the plan.

Vedanta challenged this decision in the appellate tribunal, claiming that the evaluation process did not maximise value for stakeholders and that its bid should have been considered more favourably. The tribunal, however, found no grounds to overturn the earlier approval by the National Company Law Tribunal (NCLT).

In a separate but related development, the tribunal also dismissed Vedanta’s appeal challenging aspects of the bidding process, further strengthening Adani’s position in the acquisition process.

The ruling effectively clears the way for Adani Enterprises to proceed with the acquisition of Jaiprakash Associates under the insolvency framework, subject to remaining procedural requirements.

Market observers say the decision reinforces the principle that creditor committees have broad discretion in choosing resolution plans, and judicial bodies are generally reluctant to interfere unless there is a clear procedural violation.

Also Read: RBI, IRDAI cautious on banks in commodity derivatives

Categories
Beyond

RBI, IRDAI cautious on banks in commodity derivatives

India’s financial regulators have taken a cautious stance on allowing banks and insurance companies to participate in commodity derivatives trading, according to remarks made by SEBI chief Tuhin Kanta Pandey.

Pandey said that both the Reserve Bank of India (RBI) and the Insurance Regulatory and Development Authority of India (IRDAI) are currently not inclined to permit such participation due to risk and structural concerns. As a result, banks and insurers are expected to remain out of the commodity derivatives segment for now.

The clarification comes even as the Securities and Exchange Board of India (SEBI) had earlier explored expanding participation in the commodities market to deepen liquidity and improve price discovery. SEBI had also discussed allowing banks and pension funds to enter the segment as part of efforts to strengthen the ecosystem.

However, the latest stance from the RBI and IRDAI indicates that the proposal has hit a regulatory roadblock. Officials believe commodity-linked instruments may not align with the long-term investment mandates of banks and insurance companies, and could expose them to additional volatility risks.

Following the remarks, market sentiment turned negative for commodity exchanges. Shares of Multi Commodity Exchange of India (MCX) fell by around 3–3.5%, reflecting concerns that reduced institutional participation could limit liquidity and trading volumes.

MCX, which dominates India’s commodity derivatives market, is particularly sensitive to regulatory changes affecting institutional access. Investors worry that without banks and insurers, the growth potential of the segment could be constrained in the near term.

At the same time, SEBI’s broader agenda to develop the commodity market remains in focus, including earlier proposals to involve pension funds and other long-term investors. But regulatory alignment between the three major bodies, SEBI, RBI, and IRDAI, appears to be the key hurdle.

Also Read: Spirit Airlines grounds operations, 17,000 jobs hit