Categories
Corporate

Sensex jumps over 800 points, Nifty crosses 22,450

Indian equity markets rebounded on Friday, October 9, as the Sensex and Nifty recovered from the previous session’s sharp losses, supported by strong buying in information technology stocks and improving global sentiment. The Sensex surged over 800 points during the session, while the Nifty 50 moved above the 22,450 mark, giving investors some relief after Thursday’s steep sell-off.

The rally was led by heavyweight technology companies, including Tata Consultancy Services (TCS) and Infosys, as investors responded positively to quarterly earnings and renewed interest in technology shares. Easing crude oil prices and hopes of a temporary pause in escalating tensions between the United States and Iran also helped support sentiment.

The recovery, however, remained uneven, with selling pressure in select heavyweight stocks limiting broader market gains.

IT stocks lead the recovery

Information technology shares emerged as the biggest drivers of Friday’s rally. TCS, Infosys, HCL Technologies and Tech Mahindra attracted buying interest, lifting the Nifty IT index by more than 3% during the session. TCS and Infosys rose as much as 5%, making them among the notable contributors to the benchmark indices’ advance.

Investors responded to TCS’s September-quarter performance, which showed growth in both revenue and net profit. The company’s consolidated net profit increased 15% year-on-year to ₹13,884 crore in the second quarter of FY27, compared with ₹12,075 crore in the corresponding quarter a year earlier. Revenue rose 11% to ₹73,188 crore from ₹65,799 crore.

The results helped improve confidence in the technology sector, which has faced concerns over global technology spending, changing client priorities and the possible impact of artificial intelligence on traditional IT services. Investors appeared encouraged by the company’s performance and opportunities arising from AI-led demand.

The gains in IT stocks also helped restore some confidence following the recent weakness in the broader market. However, investors are likely to track upcoming earnings announcements to assess whether the recovery can extend beyond a handful of large companies.

Banking and other heavyweight stocks support gains

Buying interest extended beyond technology shares, with several banking, consumer and industrial stocks trading higher. ITC, Adani Ports, HDFC Bank, Power Grid, Bajaj Finserv, Tata Steel, Trent, State Bank of India, Maruti Suzuki and Kotak Mahindra Bank were among the notable gainers, with some advancing by up to 3%.

The rise in banking and financial stocks provided additional support to the benchmark indices, while gains in consumer and industrial shares indicated a broader improvement in risk appetite.

However, the market did not see uniform buying across all major companies. Eternal, Reliance Industries, ICICI Bank and Bharat Electronics were among the stocks facing selling pressure at different points during the session. Their weakness highlighted the cautious approach adopted by investors despite the strong headline gains.

Sectoral performance also reflected this mixed trend. Along with IT, FMCG, public sector banks, private banks, real estate and financial services recorded gains. Pharmaceutical and oil and gas stocks, meanwhile, remained under pressure.

Crude oil prices and global developments in focus

A decline in crude oil prices offered additional support to Indian equities. Brent crude futures fell around 0.7% to $103.53 per barrel in early trade, while US West Texas Intermediate crude slipped approximately 0.6% to $90.97 per barrel.

Oil prices had risen sharply in the previous session amid concerns about potential disruptions to energy supplies from the Middle East. The subsequent easing helped reduce some pressure on oil-importing countries such as India, where elevated crude prices can increase import costs, fuel inflation and widen the current account deficit.

Comments from US President Donald Trump indicating that fresh strikes against Iran would not take place immediately also helped ease some concerns about an escalation in the conflict. Nevertheless, geopolitical uncertainty continued to weigh on sentiment, with investors closely monitoring developments in the region and the security of key shipping routes.

The movement in the rupee and US bond yields also remained important for domestic markets. A stronger rupee and easing bond yields can improve the outlook for foreign investment flows, although sustained stability in these indicators will be necessary to support a more durable recovery.

Thursday’s losses keep investors on guard

Friday’s rebound followed a difficult session on Thursday, October 8, when the Sensex plunged 1,045.46 points, or 1.44%, to close at 71,593.24. The Nifty 50 dropped 371.25 points, or 1.64%, to settle at 22,231.80.

The sharp decline reflected concerns over rising crude oil prices, rupee weakness, higher US bond yields and continued selling by foreign institutional investors. The sell-off also erased more than ₹10 lakh crore in investor wealth, underscoring the pressure on domestic equities.

Foreign institutional investors remained a key concern after reportedly recording net equity outflows of nearly ₹12,944 crore on October 8. Persistent overseas selling has weighed on large-cap stocks and contributed to the recent volatility.

Market participants will now watch whether Friday’s recovery can be sustained in the coming sessions. Movements in crude oil prices, developments in the US-Iran conflict, foreign investor activity and corporate earnings are expected to influence market direction.

Although the rally offered a welcome respite after Thursday’s sharp decline, investors may remain selective until there is greater clarity on global risks and the domestic earnings outlook. The ability of the benchmark indices to hold on to their gains will be crucial in determining whether the rebound marks the beginning of a sustained recovery or a temporary pause in the recent downturn.
 

Categories
Corporate

Sensex falls 500 points, Nifty below 22,500

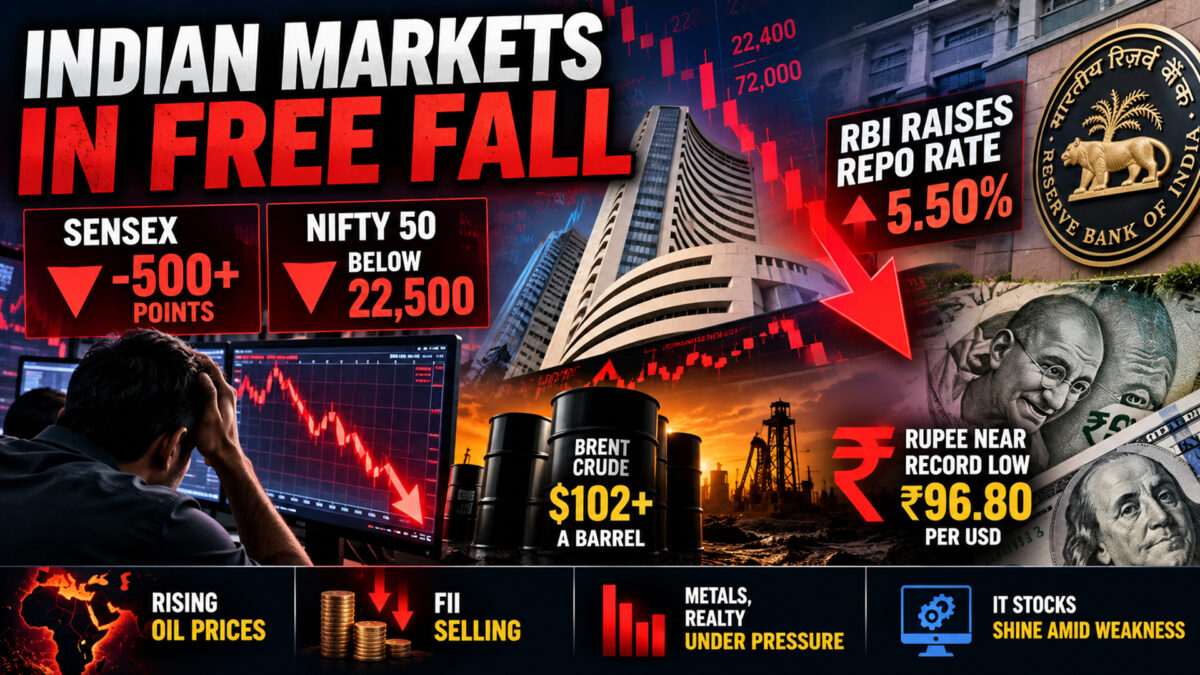
Indian stock markets came under heavy selling pressure on Thursday, with the Sensex falling more than 500 points and the Nifty 50 slipping below the 22,500 mark as investors reacted to the Reserve Bank of India’s latest policy signal, rising crude oil prices and continued foreign fund outflows.

The Sensex was trading below 72,000 around late morning, while the Nifty 50 fell below 22,400, extending the previous session’s decline. By around 11:30 am, the sharp sell-off had wiped nearly ₹7 lakh crore from the market capitalisation of companies listed on the BSE.

The weakness followed the RBI’s decision on Wednesday to raise the repo rate by 25 basis points to 5.50%, its first rate hike in nearly four years. More importantly for investors, the central bank changed its monetary policy stance from “neutral” to “calibrated tightening”.

The change has made the market more cautious because it signals that the RBI is prioritising inflation control and is not currently preparing for rate cuts. Higher interest rates can increase borrowing costs for companies and consumers, potentially affecting investment, housing demand and discretionary spending.

The RBI’s decision came at a difficult time for global markets. Brent crude climbed above $102 a barrel as concerns over supply disruptions in the Middle East and risks around the Strait of Hormuz continued to unsettle investors. Rising oil prices are particularly important for India, which depends heavily on imports to meet its energy requirements.

Higher crude prices can put pressure on inflation, widen the import bill and weigh on the Indian rupee. The rupee was trading close to ₹96.80 against the US dollar, near its record-low levels, adding another layer of uncertainty for domestic equities.

Foreign institutional investors also remained sellers. FIIs sold shares worth around ₹6,121 crore on Wednesday, while domestic institutional investors bought about ₹4,597 crore. The continued foreign selling has added to the pressure on the benchmark indices at a time when global bond yields and the dollar remain elevated.

The stock-specific action, however, offered a more mixed picture. IT stocks stood out on an otherwise weak trading day. Tech Mahindra, HCL Technologies, Tata Consultancy Services and Infosys were among the top gainers, rising as much as 2% and providing some support to the indices. Titan also featured among the gainers.

The strength in technology shares comes as investors turn their attention to the September-quarter earnings season. TCS is scheduled to announce its results later on Thursday, making the IT sector one of the key areas to watch. The market is looking for signs of improving demand, deal wins and guidance from major software exporters.

On the other side, ITC, Adani Ports, IndiGo, Power Grid and Reliance Industries were among the biggest losers on the Sensex, with several of these stocks falling sharply. ITC was down around 3%, making it one of the most prominent drags on the benchmark.

The broader market also reflected the risk-off mood. Mid-cap and small-cap stocks came under pressure, with the Nifty Midcap 100 and Nifty Smallcap 100 falling as much as 2%. Sectorally, metals were among the worst hit, with the Nifty Metal index declining around 3%. Realty, oil and gas and other rate-sensitive segments also faced selling pressure.

Market breadth remained firmly negative, showing that the selling was not restricted to a handful of heavyweight stocks. More than 2,600 stocks were in the red on the NSE, compared with fewer than 700 advances around late morning.

Analysts are now watching the 22,400-22,500 zone closely for the Nifty. A decisive break below this support could increase selling pressure and bring 22,300 into focus. On the upside, 22,800 remains an important hurdle for the index. A sustained move above that level could improve sentiment and reopen the path towards 23,000.

The immediate direction of the Indian stock market is likely to depend on a combination of factors: the trajectory of crude oil, the rupee’s movement, foreign institutional flows, global bond yields and the first set of corporate earnings. With the RBI now signalling a tighter policy approach, investors are likely to remain selective rather than chase a broad market recovery.

The focus will increasingly shift to corporate earnings, particularly from large IT companies. Strong results and positive management commentary could provide some relief to Dalal Street, but sustained recovery in the Sensex and Nifty will require greater clarity on inflation, oil prices and global geopolitical risks.


Categories
Corporate

Sensex falls 460 points, Nifty drops 22,600

Indian benchmark indices opened sharply lower on Wednesday, with the Sensex falling 460 points and the Nifty declining nearly 165 points as investors turned cautious ahead of the Reserve Bank of India’s monetary policy decision. Rising crude oil prices, continued foreign fund outflows and weakness across several heavyweight stocks added to the pressure in early trade.

The 30-share BSE Sensex fell 460 points to 72,599.05 in early trade, while the 50-share NSE Nifty declined 164.80 points to .85. The sell-off came after the indices had gained in the previous two sessions, prompting investors to lock in some profits while awaiting the RBI’s decision on interest rates.

The market later recovered significantly from its morning lows, helped by buying in banking stocks.

The RBI’s policy announcement became the biggest trigger for the market during the session. The central bank raised the repo rate by 25 basis points to 5.50%, marking its first rate increase in nearly four years. It also shifted its policy stance from neutral to calibrated tightening, signalling that further action could depend on inflation and economic growth.

The rate hike had been largely expected by investors, limiting the negative reaction after the announcement. Banking stocks, which had been under pressure in early trade, turned stronger as investors assessed the impact of higher interest rates on lenders.

Private-sector banks gained around 0.4%, while public-sector banks rose nearly 0.8%. Kotak Mahindra Bank, ICICI Bank and Axis Bank were among the key gainers and helped the broader market recover from its lows.

Higher lending rates could support bank margins initially, particularly for loans linked to external benchmarks. However, investors will also watch deposit costs and credit demand as banks adjust to the tighter interest-rate environment.

Kotak Mahindra Bank and ICICI Bank were among the leading gainers, while Titan and Asian Paints were among the major losers. Bharat Electronics, Maruti Suzuki and Mahindra & Mahindra also faced selling pressure.

Titan remained under pressure after the company reported slower jewellery growth during the September quarter. The timing of the festive season affected consumer purchases, raising concerns about near-term demand momentum. The stock’s weakness added to the pressure on the benchmark indices.

Crude oil prices provided another reason for caution. Brent crude was trading around $101.6 a barrel, keeping concerns about inflation and India’s import bill in focus. Higher oil prices can raise input and transportation costs for companies while putting pressure on the country’s external finances.

Foreign investor selling has also remained a major concern for the market. Foreign Institutional Investors sold Indian equities worth ₹2,961.30 crore on Tuesday. Domestic institutional investors have continued to provide some support, but persistent foreign outflows have made it difficult for the market to sustain strong rallies.

The broader market has already experienced a prolonged period of weakness, with Indian equities declining for eight consecutive weeks. The correction has created opportunities for bargain hunters, but investors remain cautious about making aggressive bets until there is greater clarity on interest rates, global markets and corporate earnings.

On the technical front, the 22,500-22,600 region remains an important support zone for the Nifty. A decisive break below 22,550 could push the index towards 22,400 and 22,200. On the upside, 22,850-23,000 remains an important resistance area. A sustained move above 23,000-23,100 could signal a stronger recovery.

The RBI’s economic outlook offered some comfort to investors. The central bank raised its FY27 real GDP growth forecast to 7.1%, up 40 basis points from its earlier projection. It also marginally increased its core inflation estimate to 4.4% from 4.3%.

The combination of stronger growth expectations and tighter monetary policy suggests that the RBI remains confident about the underlying economy while keeping a close watch on inflationary pressures.

Wednesday’s market action showed the competing forces currently driving Indian equities. Higher rates, expensive crude and foreign selling are weighing on sentiment, while strong domestic growth, resilient banking stocks and lower valuations are encouraging investors to buy during sharp declines.

Investors will now watch whether the Nifty can hold the 22,500-22,600 support zone and whether banking stocks can sustain the recovery through the rest of the session.

Categories
Corporate

Sensex gains 400 points, Nifty rises past 22,650

Indian equity markets extended their recovery on Tuesday, October 6, as the Sensex and Nifty traded higher, supported by buying in banking, metal and other heavyweight stocks. The rally lifted the Nifty 50 above the 22,650 mark, while the Sensex advanced more than 400 points during the session, offering investors some relief after weeks of persistent selling.

The BSE Sensex was up 355.09 points, or 0.49%, at 72,737.56, while the NSE Nifty 50 gained 111.95 points, or 0.50%, to trade at 22,667.70 around 10.48 am, according to live market updates. The benchmarks extended their gains as buying interest spread across several sectors, although weakness in information technology and healthcare stocks limited the broader advance.

The recovery followed Monday’s positive close, when the Sensex rose 472.77 points, or 0.66%, to settle at 72,382.47. The Nifty gained 133.80 points, or 0.60%, to finish at 22,555.75, snapping a four-session losing streak. The back-to-back gains suggest that investors are cautiously returning to equities after a prolonged spell of volatility.

Trent, Kotak Bank lead the rally

Retail major Trent emerged as the standout performer among Nifty 50 constituents, climbing around 10% after its quarterly business update indicated strong revenue growth. The company reported a 23% year-on-year increase in revenue in its latest update, strengthening investor interest in the stock.

Kotak Mahindra Bank was another major gainer, rising around 3.6% following its quarterly business update. The bank reported a 23.2% increase in total deposits to ₹6.51 lakh crore, compared with ₹5.28 lakh crore a year earlier. Its gross advances also increased 22.7% to ₹13.84 lakh crore, while total deposits grew 20.7% at Axis Bank, supporting sentiment across the banking sector.

Hindustan Unilever, Axis Bank and Jio Financial Services were among the other gainers on the Nifty 50. HUL advanced around 1.6%, while Axis Bank and Jio Financial Services gained approximately 1.1% and 1%, respectively.

Banking stocks remained an important source of support for the benchmarks, with investors responding to quarterly business updates and improving buying interest in private-sector lenders.

Healthcare and IT stocks lag

The gains were not uniform across the market. Max Healthcare Institute and Apollo Hospitals were among the leading Nifty 50 laggards, falling approximately 2.4% and 2%, respectively. Cipla, Tech Mahindra and ONGC also traded lower.

Information technology stocks remained under pressure, making the sector one of the notable exceptions to the broader upward movement. Healthcare stocks also faced selling, indicating that investors continued to favour selected sectors and companies rather than buying indiscriminately.

The mixed performance highlights the selective nature of the recovery. While banking and retail shares attracted strong interest, concerns surrounding valuations, earnings prospects and the wider economic outlook continued to influence individual stocks.

Metals and banking stocks support markets

Sectoral performance remained largely positive through the morning. Metal stocks advanced, with the Nifty Metal index gaining close to 1%. Private banks, financial services, power and telecom shares also recorded notable gains. Energy, pharmaceuticals and public-sector banking stocks traded higher as well.

The Nifty Private Bank index rose close to 1%, reflecting strength in lenders such as Kotak Mahindra Bank and Axis Bank. The India VIX, a measure of expected market volatility, declined around 4%, suggesting some easing in near-term nervousness among investors.

Market breadth was positive, with 2,368 shares advancing against 1,218 declining and 194 remaining unchanged at around 10.48 am. The figures indicated that buying extended beyond a handful of heavyweight stocks.

Global cues and crude oil remain in focus

Overseas markets provided some support to domestic equities. Asian shares largely traded higher, while gains on Wall Street in the previous session helped improve sentiment. However, elevated US Treasury yields and uncertainty over the global interest-rate outlook continued to pose risks for emerging markets.

Crude oil prices remained near the $100-per-barrel level despite easing from recent highs. Improved supplies from the Middle East and efforts by major economies to strengthen energy availability helped reduce some concerns about a prolonged supply disruption. Nevertheless, geopolitical tensions continued to leave oil markets vulnerable to sudden price movements.

For India, elevated crude prices remain a concern because the country depends heavily on imported oil. A sustained increase could put pressure on inflation, the rupee and corporate margins, potentially complicating the outlook for equities.

RBI policy decision in focus

Investors are also preparing for the Reserve Bank of India’s upcoming monetary policy decision, due on Wednesday. Expectations surrounding interest rates, inflation and liquidity conditions are likely to influence market direction in the near term.

Foreign institutional investors have remained net sellers, while domestic institutional investors have provided support through continued buying. This divergence has been an important factor behind recent market volatility.

The latest gains offer some encouragement, but the recovery remains fragile. Investors will watch quarterly business updates, crude oil movements, foreign fund flows and the RBI’s policy stance for clearer signals.

Tuesday’s rally shows that buyers are willing to return when valuations and company-specific developments appear attractive. Whether the momentum can be sustained, however, will depend on improving global conditions and stronger confidence in India’s near-term market outlook.


Categories
Corporate

Sensex jumps over 600 points, Nifty rises above 22,600

The Indian stock markets began the new week on a stronger note, with the Sensex jumping more than 600 points and the Nifty 50 moving above 22,600 in early trade on Monday. The rebound brought some relief to investors after both benchmark indices recorded their eighth consecutive weekly decline, marking their longest losing streak in 25 years.

The recovery was led mainly by banking and financial stocks. Bajaj Finance emerged as one of the biggest gainers, rising more than 4% after reporting an 11% year-on-year increase in new loans during the September quarter. The strong business update helped revive interest in financial stocks after weeks of heavy selling.

HDFC Bank was another major market driver, with its shares gaining around 1-2% in early trading. The stock remained in focus after the lender appointed Anup Bagchi as its new Managing Director and CEO for a three-year term. Bagchi will take charge after Sashidhar Jagdishan’s tenure ends on October 26.

Public-sector banks also attracted strong buying interest. Punjab National Bank gained nearly 3% after reporting 14.8% growth in global advances during the September quarter. Bank of Baroda rose around 2.5% after reporting an 18% increase in quarterly advances. The numbers suggested continued credit demand despite pressure on the broader market.

The banking rally extended across the sector, with the Nifty PSU Bank index gaining more than 2%. State Bank of India, Axis Bank and other major financial stocks also supported the benchmark indices.

The IT sector also contributed to the recovery, although gains were selective. The Nifty IT index rose around 1% as investors responded positively to Accenture’s better-than-expected revenue growth and strong bookings. The update offered some reassurance about global technology spending ahead of the Indian IT industry’s quarterly earnings season.

However, the rally did not lift every heavyweight. Apollo Hospitals was among the notable Nifty losers, while Infosys and Max Healthcare also traded lower. Avenue Supermarts and TVS Motor were among other stocks facing selling pressure. The mixed performance showed that investors remained selective despite the broader improvement in sentiment.

Global developments provided an additional boost. A decline in crude oil prices eased concerns over India’s import bill and inflation, while weaker-than-expected US jobs data reduced expectations of an immediate aggressive interest-rate move by the US Federal Reserve. Asian markets also largely traded higher, creating a supportive backdrop for Indian equities.

The rebound comes after a difficult stretch for the domestic market. Rising crude prices, elevated global bond yields and sustained foreign institutional investor selling have weighed on Indian equities in recent weeks. The Nifty’s fall below its 200-day moving average had also heightened concerns about the possibility of further losses.

Monday’s recovery has brought the index back towards an important technical zone. Market analysts are closely watching the 22,600-22,800 range as the immediate resistance area, while 22,200 remains an important support level. A sustained move above 22,600 could strengthen the recovery, while a break below 22,200 could bring selling pressure back.

Investors are also watching the Reserve Bank of India’s monetary policy meeting, which began on Monday. The Monetary Policy Committee is scheduled to announce its decision on Wednesday. With crude oil prices, inflation and the rupee remaining key concerns, the RBI’s policy signals could influence market direction in the coming sessions.

The Indian rupee also showed a modest improvement, gaining five paise to around ₹96.20 against the US dollar in early trade. The move offered limited relief after the currency’s recent weakness.

Monday’s rally offered a much-needed pause after weeks of relentless selling for those planning to invest. Bajaj Finance, HDFC Bank and PNB were among the key gainers, while Apollo Hospitals, Infosys and Max Healthcare remained under pressure.

The bigger question now is whether the buying momentum can hold. With the RBI policy decision, quarterly earnings, crude oil prices and foreign fund flows all in focus, volatility is likely to remain elevated. For the moment, however, Dalal Street has regained some confidence after a prolonged period of pressure.


Categories
Corporate

Sensex trades 120 points lower, Nifty stays below 22,600

Indian equity markets started October on a cautious note, with benchmark indices opening lower on Thursday as continued foreign fund outflows and weak global cues weighed on investor sentiment.


The 30-share BSE Sensex opened 120.30 points, or 0.17%, lower at 72,359.99, while the NSE Nifty50 declined 40.30 points, or 0.18%, to 22,580.15. Selling pressure remained visible across several sectors, although gains in select banking and information technology stocks offered some support.


The weak opening followed another subdued session on Wednesday. The Sensex ended 48.78 points lower at 72,480.29, while the Nifty50 slipped 95.75 points to close at 22,620.45. The benchmarks have remained under pressure as investors continue to monitor foreign fund flows, crude oil prices, the rupee and global interest-rate expectations.


Among the major Sensex stocks, Kotak Mahindra Bank, Infosys, HCL Technologies, Tata Consultancy Services and Axis Bank were among the gainers in early trade. Kotak Mahindra Bank attracted buying interest after the lender announced the appointment of Anup Kumar Saha as its new Managing Director and Chief Executive Officer for a three-year term beginning January 1, 2027.


The IT sector also provided some support to the market. The Nifty IT index gained in early trading, with Infosys, HCL Technologies and TCS among the stocks advancing. Investors were assessing recent US inflation data and its possible implications for the Federal Reserve’s interest-rate outlook. Any shift towards easier monetary conditions in the US could influence foreign flows into emerging markets, including India.


On the losing side, Mahindra & Mahindra, Maruti Suzuki, UltraTech Cement, Bharat Electronics, Eternal and Asian Paints were among the stocks under pressure. The auto sector was particularly weak, with investors tracking monthly sales numbers and demand trends.


The broader market remained cautious as selling extended beyond the headline indices. Several mid- and small-cap stocks also came under pressure, reflecting the risk-off mood at the start of the new month.


Foreign institutional selling continued to be a key concern. Foreign Institutional Investors sold Indian equities worth ₹10,148.41 crore on Wednesday, according to exchange data. Their sustained selling has remained one of the major factors weighing on domestic benchmarks in recent sessions.


Domestic institutional investors have provided some cushion through continued buying. However, the strength of domestic flows has not fully offset the impact of foreign selling, particularly as global yields remain elevated.


US Treasury yields have been closely watched by investors. The 10-year US Treasury yield remained around the 5.3% level, keeping pressure on emerging-market assets. Higher US yields can make dollar-denominated investments more attractive and can also increase the cost of capital for emerging economies.


The rupee opened weaker against the US dollar on Thursday. It started the session at ₹95.98, compared with Wednesday’s close of ₹95.83. The currency remained under pressure amid strong dollar demand and continued foreign portfolio outflows.


Crude oil prices, however, offered some relief. Brent crude was trading below the $100-a-barrel mark, providing a positive factor for India, which imports a significant share of its crude requirements. Lower oil prices can help reduce pressure on the country’s import bill, inflation and current account.


Global markets provided mixed signals. Asian equities were uneven, while investors continued to assess the outlook for US interest rates, inflation and economic growth. Markets in China and Hong Kong were closed for a holiday, limiting regional trading activity.


The domestic market’s recent weakness has also raised concerns about the duration of the ongoing correction. The Nifty and Sensex have been under pressure for several sessions, with investors becoming increasingly selective in their approach to equities.


Banking and IT stocks could remain in focus as investors look for sectors capable of providing stability amid broader volatility. At the same time, movements in automobiles, metals, cement and other cyclical sectors are likely to remain closely linked to domestic demand expectations and global commodity prices.


For investors, the immediate focus is likely to remain on foreign fund flows, crude oil prices, the rupee and US bond yields. Any improvement in global risk appetite could provide support to Indian equities, while continued foreign selling and elevated yields may keep gains limited.


As trading progresses, the ability of the Nifty to hold the 22,500-22,600 zone and the Sensex to remain above 72,000 will remain important market levels to watch. Investors are also expected to track stock-specific developments and fresh corporate announcements as the October trading session gathers pace.

Categories
Corporate

Sensex rises 100 points, Nifty holds near 22,600

Indian equities opened on a cautious note on Wednesday, with the Sensex rising around 100 points to 72,630, while the Nifty 50 traded near 22,692. The benchmarks remained volatile as investors weighed high crude oil prices, continued foreign fund outflows and mixed global cues. Selective buying in stocks such as TCS and InterGlobe Aviation offered support, while selling in Adani Ports and Max Healthcare limited gains.

The market started on a volatile note after two consecutive sessions of losses. The Sensex opened at 72,598.28, while the Nifty began at 22,712.10. The Sensex later gained more than 150 points before giving up part of the advance, while the Nifty moved above 22,700 during early trade.

Investors are entering the final trading session of September with several concerns still influencing sentiment. Rising crude oil prices, a weak rupee, foreign fund outflows and uncertainty over global developments have kept investors cautious.

Brent crude was trading around $103.5 a barrel, adding to concerns for oil-importing countries such as India. Higher crude prices can increase the country’s import bill and put pressure on inflation and the rupee. The Indian currency had closed at around ₹95.98 against the US dollar on Tuesday.

TCS, InterGlobe Aviation lead gains

Technology and aviation stocks provided support in early trade. Tata Consultancy Services (TCS) was among the leading Nifty gainers, rising around 2.5%, while InterGlobe Aviation gained nearly 2%.

Buying was also visible across parts of the broader market. Twelve of the 16 major sectoral indexes were trading higher, while small-cap and mid-cap indexes gained around 0.7% each, indicating selective buying after the recent correction.

Several stocks moved sharply following company-specific developments. KPI Green Energy gained around 2.1% after securing a solar project contract worth about $211 million in Rajasthan.

Power Mech Projects also gained after winning a contract worth around $57.2 million, while Molbio Diagnostics advanced following positive analyst coverage.

The primary market also remained active. Adroit Industries made a strong debut on Wednesday, listing at ₹250 on the BSE, an 86.57% premium to its IPO price of ₹134. On the NSE, the stock opened at ₹235, a premium of 75.37%.

Adani Ports, Max Healthcare among laggards

The gains were not broad-based, with selling pressure visible in several major stocks. Adani Ports fell around 2% in early trade, making it one of the prominent Nifty losers.

Max Healthcare declined more than 3%, while Dr Reddy’s Laboratories fell more than 2% during early trading. The weakness in these stocks offset some of the gains from technology, aviation and other sectors.

The mixed performance comes after a weak session on Tuesday. The Sensex fell 242.65 points, or 0.33%, to 72,529.07, while the Nifty declined 64.05 points, or 0.28%, to 22,716.20. Both benchmarks touched fresh six-month lows during the session.

Foreign investor selling remains another concern for the market. Foreign institutional investors sold Indian equities worth ₹9,980.22 crore on Tuesday, taking their September outflows to around $2.7 billion.

The continued selling has added pressure to Indian equities at a time when global investors are also closely tracking crude prices, currency movements and interest-rate expectations.

Global cues remain mixed

Asian markets offered mixed signals on Wednesday. Japan’s Topix gained 0.6%, Australia’s S&P/ASX 200 rose 0.7%, while China’s Shanghai Composite added 0.4%. Hong Kong’s Hang Seng, however, declined 0.4%.

US markets ended lower on Tuesday as rising Treasury yields weighed on investor sentiment. Investors are also watching upcoming US inflation and labour-market data for clues about the Federal Reserve’s interest-rate outlook.

The rupee, crude oil and foreign fund flows are likely to remain key drivers for the domestic market. A stronger dollar, elevated oil prices and continued overseas selling could keep volatility high, while easing crude prices or renewed domestic buying could provide some relief.

The recent correction has also brought valuations down across several parts of the market. The Sensex is nearly 16% below its peak of 86,159, recorded in December 2025. More than half of the BSE 500 companies with five-year valuation histories are currently trading below their five-year average valuations.

Markets are likely to remain sensitive to crude oil prices, foreign fund flows and global developments in the near term. Investors will also watch whether buying interest in select large-cap and broader market stocks can help the Sensex sustain levels above 72,600 and the Nifty hold around 22,700 after the recent sell-off.


Categories
Corporate

Sensex slides 600 points, Nifty breaches 22,650 mark

Indian stock markets remained under heavy selling pressure on Tuesday, September 29, as rising crude oil prices, a weaker rupee and continued foreign investor selling weighed on sentiment. The benchmark indices extended their recent decline, with the Sensex falling more than 600 points and the Nifty 50 slipping below the 22,600 level.

The sell-off was broad-based, with banking and financial stocks among the biggest drags on the market. Bajaj Finance, HDFC Bank, Kotak Mahindra Bank, Reliance Industries, Asian Paints and Infosys were among the key Sensex losers in early trade.

On the Nifty 50, Tata Motors Passenger Vehicles was the top loser, falling 3.05%. Bajaj Finance declined 1.59%, while Jio Financial Services dropped 1.43%. HDFC Bank was down 1.38% and Trent slipped 1.32%, adding to the pressure on the benchmark index.

Pharma and healthcare stocks offered some relief. Dr Reddy’s Laboratories emerged as the top Nifty gainer, rising 1.61%, followed by Cipla, which gained 0.87%. Apollo Hospitals advanced 0.34%, while Tech Mahindra and Coal India added 0.32% and 0.21%, respectively.

The sharp decline in equities came against a backdrop of rising crude oil prices. Brent crude was trading around $106.86 a barrel, extending its gains from the previous session. Investors remained cautious over the possibility of supply disruptions from the Middle East amid continuing tensions involving the US and Iran.

Crude oil is particularly important for the Indian economy because the country depends heavily on imports to meet its energy requirements. A sustained rise in oil prices can increase the country’s import bill and put pressure on the current account and inflation outlook. Higher crude prices can also weigh on corporate margins in sectors that are dependent on fuel and transportation costs.

The impact was visible in currency markets as well. The Indian rupee opened at 96.03 against the US dollar and weakened further to 96.13 during early trading. It had closed at 95.97 on Monday. The combination of expensive crude oil and foreign fund outflows has kept the rupee under pressure.

Foreign institutional investors have remained cautious towards Indian equities. FIIs sold shares worth ₹3,693.93 crore on Friday, adding to concerns about continued overseas selling. Persistent FII outflows can increase pressure on domestic benchmarks, particularly when global risk appetite is weak.

Global market cues also remained mixed. Asian equities largely traded lower, with Japan’s Nikkei 225, South Korea’s KOSPI and Hong Kong’s Hang Seng under pressure. The Shanghai Composite was marginally higher. Rising US Treasury yields have also added to concerns in global equity markets as investors assess the outlook for interest rates and economic growth.

The weakness was spread across several sectors on the domestic market. Banking, financial services and private bank stocks were among the major laggards. FMCG, oil and gas, consumer durables and cement stocks also faced selling pressure. The relative strength in pharmaceutical and healthcare stocks provided limited support as the broader market remained weak.

Despite the overall decline, several stocks attracted buying interest. Ellenbarrie Industrial Gases gained around 5% after receiving a ₹481-crore order from Bharat Heavy Electricals Limited (BHEL). The order-related development helped the stock outperform the broader market.

Varmora Granito also made a positive debut on Tuesday. The stock listed at ₹155 on the NSE, compared with its issue price of ₹148, marking a 4.73% premium. The listing came even as broader market sentiment remained weak.

PB Fintech was another stock in focus during the session. The company’s shares gained around 4% after Bernstein retained its Outperform rating with a target price of ₹2,310. The stock had faced sharp selling in the previous two sessions following concerns over proposed changes to insurance distribution regulations.

Investors are now closely watching developments in crude oil, the rupee, foreign fund flows and global bond yields for signs of how the market could move ahead. Geopolitical developments in the Middle East remain another important factor for global markets.

The recent weakness has also brought the focus back to valuation and earnings expectations. With the Sensex and Nifty already trading close to six-month lows, market participants are looking for stability after several sessions of selling.

The immediate market mood remains cautious. Elevated crude prices, a weaker rupee, FII selling and pressure on banking and financial stocks are keeping investors on edge, while select pharma, healthcare and company-specific stocks are continuing to attract buying interest.


Categories
Corporate

Sensex sheds over 900 points, Nifty drops below 22,900

Equity markets came under heavy selling pressure on Monday, with the Sensex plunging more than 900 points and the Nifty 50 slipping below 22,900 as rising crude oil prices, foreign fund outflows and geopolitical uncertainty weighed on investor sentiment.

The Sensex fell nearly 1,000 points during morning trade, while the Nifty dropped below the crucial 23,000 mark and moved towards 22,900. The sharp decline came after both benchmarks had already recorded their seventh consecutive weekly fall last week.

The selling was broad-based, with investors cutting exposure across several sectors. Banking and financial stocks were among the major drags, while technology, healthcare and other key sectors also faced pressure.

Crude oil remained one of the biggest concerns for investors. Brent crude moved above $106 a barrel amid uncertainty over developments involving the US and Iran and concerns around supplies through the Strait of Hormuz.

Higher oil prices are particularly important for India because the country depends heavily on crude imports. A sustained rise in prices can increase the import bill, put pressure on the rupee and add to inflation concerns. It can also squeeze corporate margins, particularly for companies with high fuel and transportation costs.

The Indian rupee also remained under pressure against the US dollar, adding to concerns about the broader economic impact of higher crude prices. A weaker rupee makes imports more expensive and can further complicate the inflation outlook.

Foreign selling weighs on Dalal Street

Continued foreign institutional investor selling has emerged as another major pressure point for the Indian stock market. Foreign investors sold equities worth around ₹3,694 crore on September 25, while domestic institutional investors bought shares worth about ₹2,838 crore.

Persistent foreign outflows, elevated US bond yields and uncertainty around global interest rates have kept investors cautious. Domestic buying has provided some support, but it has not been enough to completely offset overseas selling.

The sharp fall on Monday also erased much of the optimism created by Friday’s recovery. The Sensex had gained 315 points in the previous session, while the Nifty rose more than 77 points. However, the recovery failed to change the broader market trend.

Axis Bank, Asian Paints among gainers

Despite the broad sell-off, a few stocks managed to remain in positive territory. Axis Bank, Asian Paints, HCL Technologies and Mahindra & Mahindra were among the Nifty stocks showing relative strength in early trade.

Their gains stood out against the wider market decline, highlighting the stock-specific nature of trading even during a sharp correction.

On the other side, Infosys, Max Healthcare and Tata Motors Passenger Vehicles were among the notable Nifty losers. The selling reflected continued weakness in several heavyweight and large-cap counters.

The broader market was also under pressure, with mid-cap and small-cap stocks witnessing declines as investors turned cautious and reduced risk exposure.

Adani Power, SAIL in focus

Several stocks remained in focus because of company-specific developments.

Adani Power completed the merger of 10 wholly owned subsidiaries as part of its restructuring exercise. The merger became effective on September 25.

SAIL and Bharat Coking Coal Ltd entered into an agreement to jointly develop and operate two coal blocks in West Bengal. The blocks have a combined peak rated capacity of around 4 million tonnes a year.

Ola Electric also remained on investors’ radar after announcing that its board would meet to consider a proposal to raise funds through a rights issue.

These developments provided individual stock cues even as the broader market remained dominated by macroeconomic concerns.

Crude, rupee and global cues in focus

Investors will closely track crude oil prices, foreign fund flows, the rupee and global market trends for further direction. Developments surrounding the US-Iran situation and the Strait of Hormuz could remain particularly important for oil prices and emerging-market sentiment.

The Nifty’s fall below 23,000 has also put the spotlight on key support levels as traders assess whether the current correction could deepen. Market volatility is expected to remain elevated as investors balance domestic fundamentals with global risks.

With crude oil prices above $106 a barrel, continued FII selling and pressure on the rupee, Sensex today and Nifty today are likely to remain closely watched. Monday’s sell-off has once again underlined how quickly global developments can influence Indian equities and investor sentiment.


Categories
Corporate

Sensex opens 150 points higher, Nifty above 23,090

Indian benchmark indices opened higher on Friday, September 25, as investors returned to select beaten-down stocks following the sharp selloff in the previous session. The Sensex gained more than 150 points at the open, while the Nifty 50 moved above the 23,090 level.

The Sensex opened at 73,736.36, up 155.82 points, or 0.21%, from its previous close. The Nifty 50 opened at 23,095.70, gaining 32.60 points, or 0.14%.

The opening recovery followed a difficult session on Thursday, when both benchmarks recorded their steepest single-day fall in several weeks. The Sensex had plunged 1,247.71 points, or 1.67%, to 73,580.54, while the Nifty fell 383.70 points, or 1.64%, to 23,063.10.

Friday’s early gains reflected some value buying after the sharp correction. However, investors remained cautious as crude oil prices, global bond yields, foreign fund flows and geopolitical developments continued to influence market sentiment.

Financial stocks support recovery

Financial and auto stocks were among the early gainers on Friday. Bajaj Finserv, Shriram Finance, Power Grid, Bajaj Auto and Axis Bank were among the leading Nifty gainers.

Bajaj Finserv rose around 0.7%, while Shriram Finance gained about 0.6%. Power Grid, Bajaj Auto and Axis Bank also traded higher.

Other stocks providing support included ICICI Bank, Larsen & Toubro, Mahindra & Mahindra, State Bank of India, Bharti Airtel and Bajaj Finance.

The broader market also showed signs of recovery, with buying spread across several large- and mid-cap stocks. Domestic institutional investors have continued to provide support to Indian equities even as foreign investors remain net sellers.

IT stocks drag benchmarks

Information technology stocks remained under pressure during early trading. Infosys, TCS, Wipro, ONGC and Tech Mahindra were among the prominent Nifty losers.

Infosys fell more than 2% in early trade, while TCS declined close to 2%. Wipro and Tech Mahindra also traded lower.

The weakness in IT stocks offset some of the gains in banking, financial and auto shares. Technology companies remain sensitive to global economic conditions, US demand and currency movements, while elevated global bond yields have also affected investor sentiment towards growth-oriented stocks.

Crude oil remains key concern

Crude oil prices remained a major factor for Indian markets. Brent crude was trading above $105 a barrel, although prices eased from recent levels.

Investors are closely monitoring developments in the Middle East, particularly the US-Iran situation and risks to oil supplies. Higher crude prices are a concern for India because the country depends heavily on imports to meet its energy requirements.

Sustained high oil prices could increase pressure on inflation, the current account balance and the Indian rupee. A moderation in crude prices, on the other hand, could offer some relief to the domestic economy and corporate margins.

Rupee, FII flows in focus

The Indian rupee opened marginally stronger at around ₹95.90 against the US dollar, compared with its previous close of ₹95.96.

Currency movements remain closely linked to crude prices and foreign capital flows. A weaker rupee can raise the cost of imported commodities, particularly crude oil, while also increasing pressure on companies with significant foreign-currency exposure.

Foreign institutional investors continued to sell Indian equities. FIIs sold shares worth around ₹5,027 crore on Thursday, while domestic institutional investors bought equities worth approximately ₹4,301 crore.

The strong participation of domestic investors has helped cushion the impact of foreign outflows in recent sessions. However, sustained FII selling remains a concern for the near-term direction of the market.

Global cues remain mixed

Asian markets provided mixed signals on Friday as investors assessed interest-rate expectations, geopolitical developments and the outlook for global growth.

US Treasury yields remained elevated, keeping pressure on emerging-market assets. Higher US yields can make dollar-denominated assets more attractive and may encourage foreign investors to reduce exposure to riskier markets.

Investors are therefore watching developments in US interest rates alongside crude oil and geopolitical risks.

NSE shares remain in focus

The newly listed National Stock Exchange (NSE) also remained in focus after making its stock-market debut on Thursday.

NSE shares gained around 2% on the first day of trading and closed at ₹1,818 against the issue price of ₹1,785. The listing has added another closely watched stock to the Indian equity market.

For the broader market, Friday’s early recovery comes after a sharp correction and does not eliminate the concerns that triggered Thursday’s selloff. Crude oil prices, foreign fund flows, the rupee, global bond yields and developments in the Middle East are expected to remain key market drivers.

The immediate focus will be on whether the Nifty can sustain levels above 23,050-23,100 and whether buying interest broadens beyond financial and auto stocks. Continued weakness in IT majors could limit the recovery.

With global cues remaining uncertain, investors are likely to remain selective. The ability of domestic institutional buying to absorb foreign selling, along with movements in crude oil and the rupee, will be closely watched as trading progresses.